






War or recovery? H1 earnings reshuffle petchem winners and losers
by Esra Ersöz - eersoz@chemorbis.com

The Middle East war sharply altered the global petrochemical landscape in the second quarter of 2026, but the financial impact was far from uniform. First-half results from major producers reveal a widening divide between companies directly exposed to production, feedstock and logistics disruptions and those able to capitalize on the resulting supply squeeze, higher prices and shifting feedstock economics.
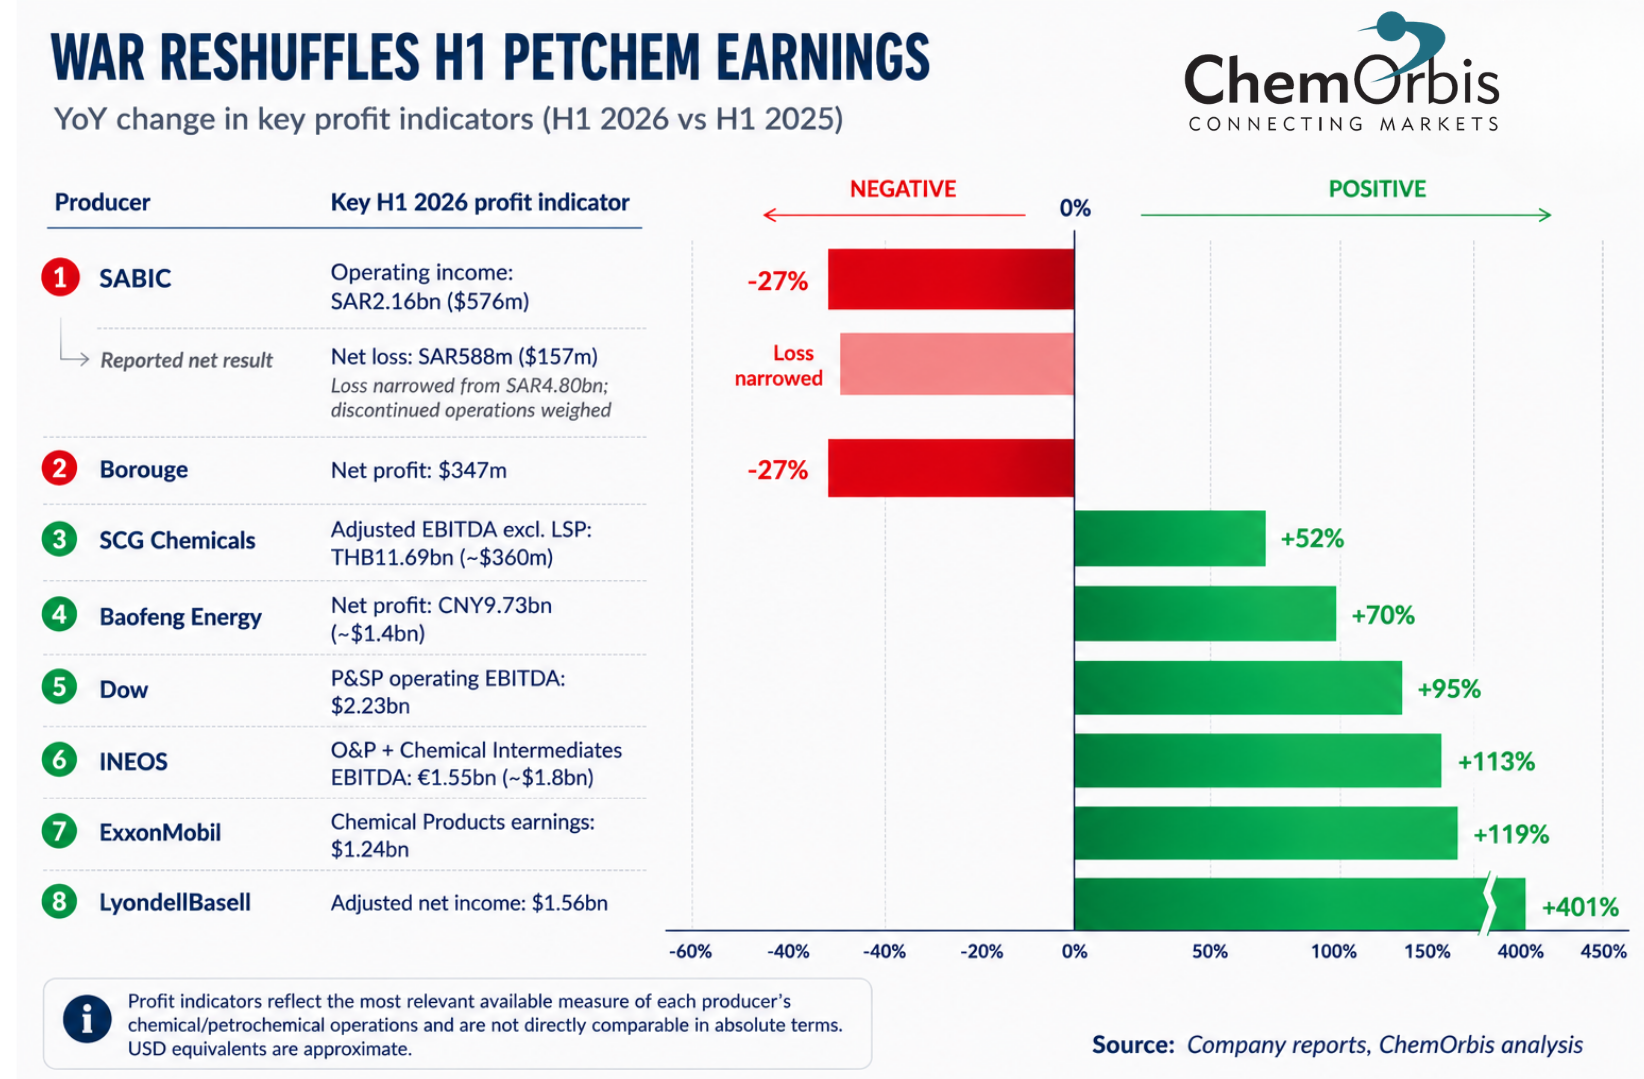
The divergence is striking. Key profit indicators for SABIC and Borouge fell by around a quarter year on year, while LyondellBasell, Dow, ExxonMobil’s chemical business, INEOS and SCG Chemicals recorded substantial increases on their respective adjusted operating metrics. In China, Baofeng Energy also emerged as a major winner as soaring crude prices strengthened the relative economics of coal-based olefins.
Yet the results do not point to a conventional petrochemical recovery. Demand remained lackluster across many markets, while volumes at several of the best-performing producers were hardly booming. Instead, the war temporarily removed or constrained supply and redistributed margins toward producers that could keep plants running, secure feedstocks and reach customers.
Gulf producers bear the brunt, but higher prices provide a cushion
For producers closest to the disruption, the war presented a paradox: product prices surged as availability tightened, but producing and moving enough material to capture those gains became considerably harder.
SABIC’s H1 revenue fell 14% year on year to SAR50.96 billion, while income from operations declined 27% to SAR2.16 billion. The Saudi major remained in the red at the bottom line, although its reported net loss narrowed substantially to SAR588 million from SAR4.80 billion a year earlier. The latter comparison was heavily influenced by discontinued operations, making operating income a more useful indicator of underlying performance.
The impact of the war became particularly visible in Q2. Supply-chain disruption and changing trade flows hit sales volumes, even as sharply higher selling prices provided a partial cushion. SABIC responded by rerouting material, including increased polymer movements from Saudi Arabia’s east coast to the west, but the disruption still left the company on the losing side of the H1 earnings divide.
Borouge provides another clear example. H1 net profit fell 27% year on year to $347 million, while adjusted EBITDA declined 26% to $744 million. Sales volumes were down 18% at 1.96 million tons.
Yet Borouge’s experience also shows why the war’s impact cannot be reduced simply to geography. The UAE producer developed alternative logistics routes and continued moving material despite the disruption. By Q2, realized prices had risen sharply and quarterly net profit improved from Q1, although lower volumes and elevated feedstock and logistics costs continued to weigh on the year-on-year comparison.
Other Gulf producers underline this divergence. Saudi Kayan and Sipchem suffered from weaker volumes and higher costs, while Yansab moved in the opposite direction, posting its strongest quarterly profit since 2022 as reliable operations allowed it to capture higher selling prices.
The dividing line, therefore, was not simply whether a producer was located in the Middle East. The ability to remain operational and get products to market became critical to turning the war-driven price rally into profit.
LYB and INEOS capture the supply squeeze
If Middle Eastern producers were dealing with the physical consequences of disruption, several Western majors found themselves on the other side of the equation.
LyondellBasell’s adjusted H1 net income surged to $1.56 billion, more than five times the year-earlier level. The company explicitly linked the Q2 improvement to geopolitical instability and tighter global supply, raising North American operating rates to capitalize on stronger margins.
The mechanism was straightforward. Reduced Middle Eastern supply and feedstock shortages that curtailed production elsewhere tightened availability just as crude and naphtha prices rose. For North American ethane-based production, the result was a stronger relative cost position and substantially better polymer economics.
INEOS provides perhaps the clearest evidence. H1 EBITDA across its Olefins & Polymers and Chemical Intermediates businesses more than doubled to €1.55 billion from €728 million. Q2 alone generated €1.13 billion of EBITDA versus €312 million a year earlier.
INEOS directly attributed the shift to the Middle East conflict. Reduced exports from the region tightened supply, while feedstock shortages slowed Asian production. At the same time, low ethane prices strengthened North America’s cost advantage. Even Europe benefited as lower import pressure allowed prices and margins to rise.
O&P Europe was particularly striking: Q2 EBITDA jumped to €452 million from just €61 million a year earlier. O&P North America rose to €373 million from €118 million.
That is important because it challenges the assumption that soaring crude prices would automatically leave Europe’s naphtha-heavy petrochemical industry among the losers. During Q2, the benefit from tighter supply and reduced imports was strong enough to outweigh much of the feedstock pressure.
Dow and Exxon: Earnings jump without a demand boom
Dow offers another indication that the improvement was primarily margin-led rather than demand-led.
Its Packaging & Specialty Plastics business, which encompasses much of Dow’s ethylene and PE chain, generated H1 operating EBITDA of $2.23 billion, almost double the year-earlier level. The turnaround was heavily concentrated in Q2 as sharply higher PE prices boosted integrated margins.
This is particularly telling because the first quarter had shown little sign of an industry recovery. Before the full effect of the Middle East disruption was felt, Dow was still pointing to soft global demand and pressure from feedstock and energy costs.
ExxonMobil followed a similar pattern. Its Chemical Products business generated around $1.24 billion of H1 earnings, more than double the $566 million reported a year earlier. Exxon had reported just $110 million of Chemical Products earnings in Q1, meaning the dramatic improvement was concentrated in Q2. Exxon defines Chemical Products as its petrochemicals and advanced-recycling business, making the segment a considerably cleaner indicator for this analysis than the oil major’s consolidated earnings.
China’s coal route emerges as a clear winner
China offers perhaps the starkest example of how the war reordered feedstock competitiveness.
Ningxia Baofeng Energy Group, one of China’s largest coal-to-chemicals producers, reported record H1 net profit of CNY9.73 billion ($1.4 billion), up 70% year on year.
The war sharply increased crude-linked feedstock costs for oil-based olefins producers, while propane-based producers also faced higher costs and disrupted supply. Coal prices in China moved much less dramatically, widening the relative cost advantage of coal-to-olefins production. Baofeng itself pointed to the sharp increase in oil-based olefin feedstock costs compared with only modest increases in coal-based production costs.
Higher output following the ramp-up of Baofeng’s Inner Mongolia project also contributed to the earnings increase, meaning its H1 performance cannot be attributed solely to the war. Still, the conflict amplified an existing feedstock advantage and demonstrated how geopolitical disruption can rapidly reorder China’s already diverse olefins cost curve.
Southeast Asia turns disruption into margin gains
SCG Chemicals illustrates how supply-chain flexibility allowed a producer initially hit by the disruption to ultimately emerge on the positive side of the H1 earnings divide.
The closure of the Strait of Hormuz initially hit the company directly. Rayong Olefins declared force majeure and temporarily suspended operations in March because restrictions on feedstock flows prevented it from securing key raw materials.
SCGC subsequently accelerated feedstock procurement from non-Hormuz origins, while tighter global petrochemical supply lifted PE and PP prices and improved spreads. On an adjusted basis excluding Long Son Petrochemicals (LSP), SCGC’s H1 EBITDA rose 52% year on year to THB11.69 billion (~$360 million), with the company citing higher product spreads as a key driver.
The result highlights the two-sided nature of the shock for Asian producers dependent on imported feedstocks. The same disruption that initially threatened production also tightened downstream markets and improved product pricing. By diversifying feedstock sourcing and optimizing operations, SCGC was able to turn that supply shock into stronger underlying earnings.
Supply-chain flexibility therefore became almost as important as the underlying feedstock cost itself.
War premium or genuine recovery?
At first glance, the H1 earnings numbers resemble the beginning of a strong petrochemical upcycle. For several major producers, profitability increased by 50%, 70%, 100% or even more year on year.
But the underlying picture tells a different story.
That distinction will become increasingly important in H2. If Middle Eastern production and trade flows normalize, the exceptional supply premium that supported margins elsewhere could fade, leaving producers once again facing the industry’s pre-war realities of excess capacity, subdued demand and intense competition.
The real test for the H1 winners will therefore be whether their earnings improvement can survive the normalization of supply, or whether the first-half surge ultimately proves to have been a war premium rather than the start of a sustainable petrochemical recovery.
The divergence is striking. Key profit indicators for SABIC and Borouge fell by around a quarter year on year, while LyondellBasell, Dow, ExxonMobil’s chemical business, INEOS and SCG Chemicals recorded substantial increases on their respective adjusted operating metrics. In China, Baofeng Energy also emerged as a major winner as soaring crude prices strengthened the relative economics of coal-based olefins.
Yet the results do not point to a conventional petrochemical recovery. Demand remained lackluster across many markets, while volumes at several of the best-performing producers were hardly booming. Instead, the war temporarily removed or constrained supply and redistributed margins toward producers that could keep plants running, secure feedstocks and reach customers.
Gulf producers bear the brunt, but higher prices provide a cushion
For producers closest to the disruption, the war presented a paradox: product prices surged as availability tightened, but producing and moving enough material to capture those gains became considerably harder.
SABIC’s H1 revenue fell 14% year on year to SAR50.96 billion, while income from operations declined 27% to SAR2.16 billion. The Saudi major remained in the red at the bottom line, although its reported net loss narrowed substantially to SAR588 million from SAR4.80 billion a year earlier. The latter comparison was heavily influenced by discontinued operations, making operating income a more useful indicator of underlying performance.
The impact of the war became particularly visible in Q2. Supply-chain disruption and changing trade flows hit sales volumes, even as sharply higher selling prices provided a partial cushion. SABIC responded by rerouting material, including increased polymer movements from Saudi Arabia’s east coast to the west, but the disruption still left the company on the losing side of the H1 earnings divide.
Borouge provides another clear example. H1 net profit fell 27% year on year to $347 million, while adjusted EBITDA declined 26% to $744 million. Sales volumes were down 18% at 1.96 million tons.
Yet Borouge’s experience also shows why the war’s impact cannot be reduced simply to geography. The UAE producer developed alternative logistics routes and continued moving material despite the disruption. By Q2, realized prices had risen sharply and quarterly net profit improved from Q1, although lower volumes and elevated feedstock and logistics costs continued to weigh on the year-on-year comparison.
Other Gulf producers underline this divergence. Saudi Kayan and Sipchem suffered from weaker volumes and higher costs, while Yansab moved in the opposite direction, posting its strongest quarterly profit since 2022 as reliable operations allowed it to capture higher selling prices.
The dividing line, therefore, was not simply whether a producer was located in the Middle East. The ability to remain operational and get products to market became critical to turning the war-driven price rally into profit.
LYB and INEOS capture the supply squeeze
If Middle Eastern producers were dealing with the physical consequences of disruption, several Western majors found themselves on the other side of the equation.
LyondellBasell’s adjusted H1 net income surged to $1.56 billion, more than five times the year-earlier level. The company explicitly linked the Q2 improvement to geopolitical instability and tighter global supply, raising North American operating rates to capitalize on stronger margins.
The mechanism was straightforward. Reduced Middle Eastern supply and feedstock shortages that curtailed production elsewhere tightened availability just as crude and naphtha prices rose. For North American ethane-based production, the result was a stronger relative cost position and substantially better polymer economics.
INEOS provides perhaps the clearest evidence. H1 EBITDA across its Olefins & Polymers and Chemical Intermediates businesses more than doubled to €1.55 billion from €728 million. Q2 alone generated €1.13 billion of EBITDA versus €312 million a year earlier.
INEOS directly attributed the shift to the Middle East conflict. Reduced exports from the region tightened supply, while feedstock shortages slowed Asian production. At the same time, low ethane prices strengthened North America’s cost advantage. Even Europe benefited as lower import pressure allowed prices and margins to rise.
O&P Europe was particularly striking: Q2 EBITDA jumped to €452 million from just €61 million a year earlier. O&P North America rose to €373 million from €118 million.
That is important because it challenges the assumption that soaring crude prices would automatically leave Europe’s naphtha-heavy petrochemical industry among the losers. During Q2, the benefit from tighter supply and reduced imports was strong enough to outweigh much of the feedstock pressure.
Dow and Exxon: Earnings jump without a demand boom
Dow offers another indication that the improvement was primarily margin-led rather than demand-led.
Its Packaging & Specialty Plastics business, which encompasses much of Dow’s ethylene and PE chain, generated H1 operating EBITDA of $2.23 billion, almost double the year-earlier level. The turnaround was heavily concentrated in Q2 as sharply higher PE prices boosted integrated margins.
This is particularly telling because the first quarter had shown little sign of an industry recovery. Before the full effect of the Middle East disruption was felt, Dow was still pointing to soft global demand and pressure from feedstock and energy costs.
ExxonMobil followed a similar pattern. Its Chemical Products business generated around $1.24 billion of H1 earnings, more than double the $566 million reported a year earlier. Exxon had reported just $110 million of Chemical Products earnings in Q1, meaning the dramatic improvement was concentrated in Q2. Exxon defines Chemical Products as its petrochemicals and advanced-recycling business, making the segment a considerably cleaner indicator for this analysis than the oil major’s consolidated earnings.
Together, the results from LYB, Dow, Exxon and INEOS point to a common theme: the biggest earnings gains did not require a major recovery in end-user demand. The removal or disruption of competing supply was enough to restore pricing power and widen margins dramatically.
China’s coal route emerges as a clear winner
China offers perhaps the starkest example of how the war reordered feedstock competitiveness.
Ningxia Baofeng Energy Group, one of China’s largest coal-to-chemicals producers, reported record H1 net profit of CNY9.73 billion ($1.4 billion), up 70% year on year.
The war sharply increased crude-linked feedstock costs for oil-based olefins producers, while propane-based producers also faced higher costs and disrupted supply. Coal prices in China moved much less dramatically, widening the relative cost advantage of coal-to-olefins production. Baofeng itself pointed to the sharp increase in oil-based olefin feedstock costs compared with only modest increases in coal-based production costs.
Higher output following the ramp-up of Baofeng’s Inner Mongolia project also contributed to the earnings increase, meaning its H1 performance cannot be attributed solely to the war. Still, the conflict amplified an existing feedstock advantage and demonstrated how geopolitical disruption can rapidly reorder China’s already diverse olefins cost curve.
Southeast Asia turns disruption into margin gains
SCG Chemicals illustrates how supply-chain flexibility allowed a producer initially hit by the disruption to ultimately emerge on the positive side of the H1 earnings divide.
The closure of the Strait of Hormuz initially hit the company directly. Rayong Olefins declared force majeure and temporarily suspended operations in March because restrictions on feedstock flows prevented it from securing key raw materials.
SCGC subsequently accelerated feedstock procurement from non-Hormuz origins, while tighter global petrochemical supply lifted PE and PP prices and improved spreads. On an adjusted basis excluding Long Son Petrochemicals (LSP), SCGC’s H1 EBITDA rose 52% year on year to THB11.69 billion (~$360 million), with the company citing higher product spreads as a key driver.
The result highlights the two-sided nature of the shock for Asian producers dependent on imported feedstocks. The same disruption that initially threatened production also tightened downstream markets and improved product pricing. By diversifying feedstock sourcing and optimizing operations, SCGC was able to turn that supply shock into stronger underlying earnings.
Supply-chain flexibility therefore became almost as important as the underlying feedstock cost itself.
War premium or genuine recovery?
At first glance, the H1 earnings numbers resemble the beginning of a strong petrochemical upcycle. For several major producers, profitability increased by 50%, 70%, 100% or even more year on year.
But the underlying picture tells a different story.
- Global petrochemical overcapacity did not disappear. China’s capacity expansion continued, end-user demand remained uneven, and Europe’s structural cost disadvantage was not resolved. Instead, the Middle East war temporarily changed the amount and cost of supply available to the global market.
- The winners were generally producers able to keep plants operating, access relatively advantageous feedstocks or secure alternative raw materials and logistics while competitors struggled. The losers were more exposed to physical supply-chain disruption, lost production and sharply higher costs.
- Even that distinction was not absolute. Yansab’s strong performance shows that a producer inside the affected region could capture the price rally if its plants remained reliable, while SCGC demonstrates that a producer initially exposed to direct feedstock disruption could still emerge as a winner by securing alternative supply and capitalizing on stronger spreads.
The message from H1 earnings is clear: for most of the winners, the profit surge came from war-driven supply tightness and stronger margins, not from a meaningful recovery in demand.
That distinction will become increasingly important in H2. If Middle Eastern production and trade flows normalize, the exceptional supply premium that supported margins elsewhere could fade, leaving producers once again facing the industry’s pre-war realities of excess capacity, subdued demand and intense competition.
The real test for the H1 winners will therefore be whether their earnings improvement can survive the normalization of supply, or whether the first-half surge ultimately proves to have been a war premium rather than the start of a sustainable petrochemical recovery.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?
- EU publishes tariff regulation, swings doors wide open to duty-free US plastics
- Stats: China rewrites PE trade dynamics as April exports explode amid Middle East disruptions
- Role reversal: Iran seeks polymers from Türkiye amid war disruptions
- US PE cracks after record highs; corrections spread from Asia to Europe and Türkiye

