







Asia PET prices extend losses into November on sluggish demand, weaker feedstocks
by Pınar Polat - ppolat@chemorbis.com

In Asia, the downtrend in PET prices that kicked off by the middle of September has continued this week as buying appetite has remained lackluster due to strengthening economic headwinds.
While depreciating local currencies have made import trading even harder, weakening feedstock prices have also contributed to the losses. Compared to three weeks ago, spot prices on CFR China basis are down by around 13-13.5% for paraxylene, PTA and MEG, ChemOrbis data show.
FOB China offers at/above $1000 disappear
In China, export PET bottle offers were assessed stable to $20/ton lower from last week at $960-980/ton FOB, cash basis.
Local PET prices in China were also assessed CNY300/ton ($41/ton) lower on both ends from last week at CNY6,850-7,200/ton ($840-883/ton excl. VAT) ex-warehouse China, cash inc. VAT basis.
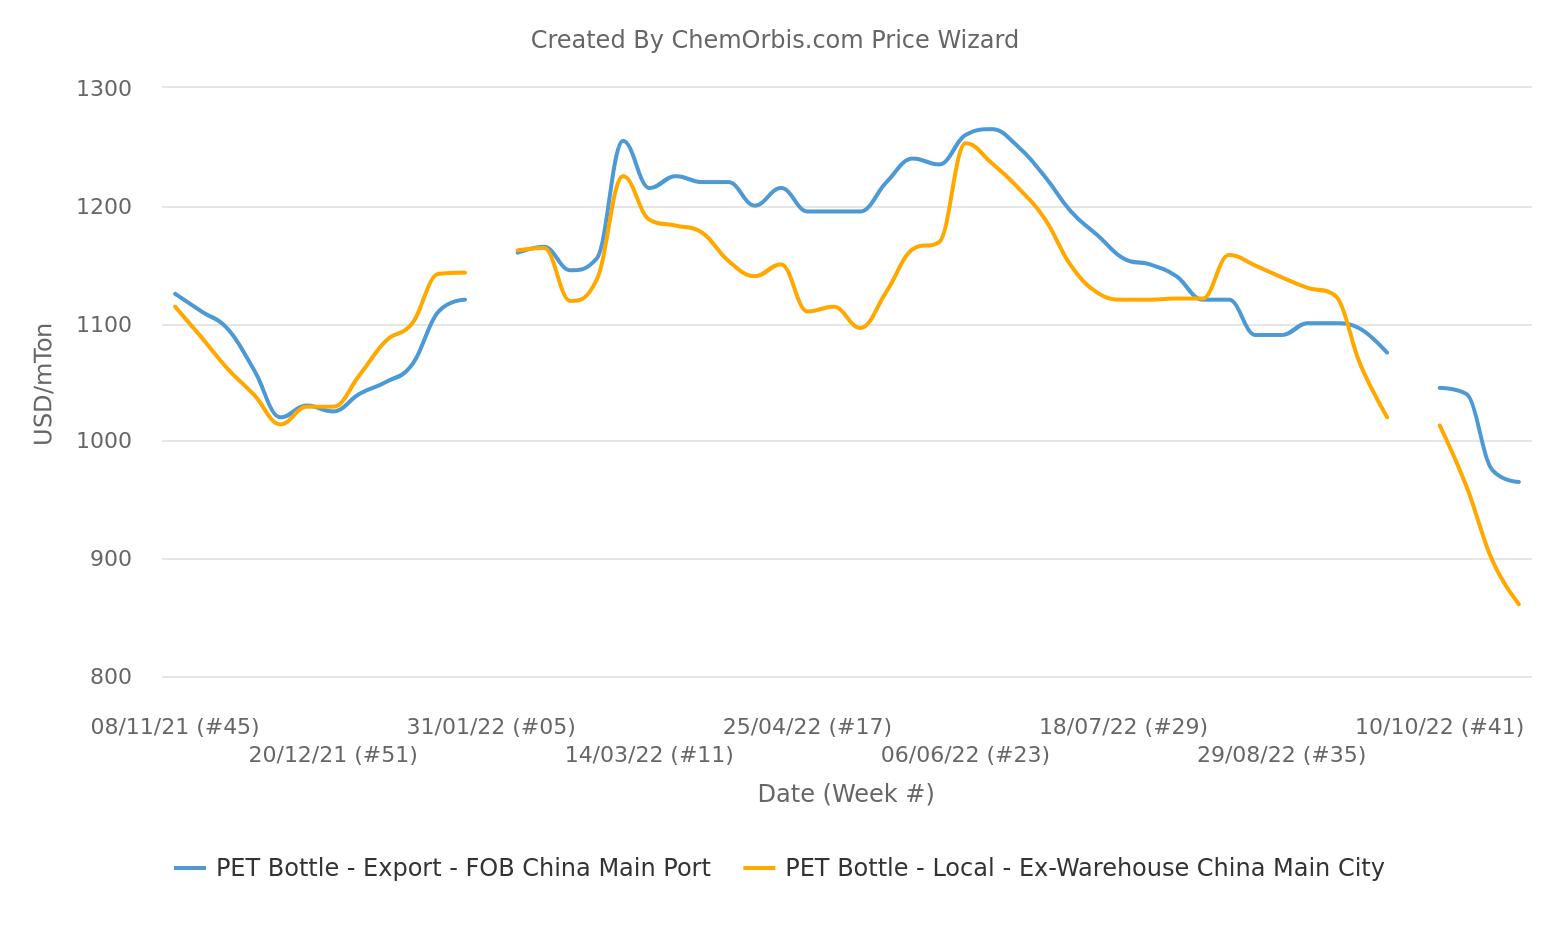
A Chinese producer cut export PET prices further by $20-30/ton from last week and a company source said, “The key PX/PTA and MEG feedstock prices have continued to slide, and regional demand has stayed bearish on slowing economic growth amid rising inflation. Local PET prices have also corrected sharply.”
FOB South Korea and CIF SEA offers fall in line with China
In South Korea, export PET bottle prices were assessed $30/ton lower from last week at $1020-1030/ton FOB Busan.
A major South Korean producer underlined, “Regional demand remains sluggish on China’s ongoing zero-Covid policy, as well as the region’s slow economic growth. Depreciating Asian currencies against the US dollar have also hindered demand. Suppliers and buyers are not expecting much of a China or regional demand recovery this year.”
In Southeast Asia, import PET bottle prices for all origins were assessed $20/ton lower from last week at $940-1040/ton on CIF, cash basis. Chinese offers were assessed at $940-1000/ton, while South Korean offers stayed at the high end.
Southeast Asian players have mostly preferred to wait as prices were expected to fall further in the weeks ahead. “We’re not in a rush to replenish as we’ve enough stocks for another 1-2 months,” a Vietnamese converter said.
While depreciating local currencies have made import trading even harder, weakening feedstock prices have also contributed to the losses. Compared to three weeks ago, spot prices on CFR China basis are down by around 13-13.5% for paraxylene, PTA and MEG, ChemOrbis data show.
FOB China offers at/above $1000 disappear
In China, export PET bottle offers were assessed stable to $20/ton lower from last week at $960-980/ton FOB, cash basis.
Local PET prices in China were also assessed CNY300/ton ($41/ton) lower on both ends from last week at CNY6,850-7,200/ton ($840-883/ton excl. VAT) ex-warehouse China, cash inc. VAT basis.
A Chinese producer cut export PET prices further by $20-30/ton from last week and a company source said, “The key PX/PTA and MEG feedstock prices have continued to slide, and regional demand has stayed bearish on slowing economic growth amid rising inflation. Local PET prices have also corrected sharply.”
FOB South Korea and CIF SEA offers fall in line with China
In South Korea, export PET bottle prices were assessed $30/ton lower from last week at $1020-1030/ton FOB Busan.
A major South Korean producer underlined, “Regional demand remains sluggish on China’s ongoing zero-Covid policy, as well as the region’s slow economic growth. Depreciating Asian currencies against the US dollar have also hindered demand. Suppliers and buyers are not expecting much of a China or regional demand recovery this year.”
In Southeast Asia, import PET bottle prices for all origins were assessed $20/ton lower from last week at $940-1040/ton on CIF, cash basis. Chinese offers were assessed at $940-1000/ton, while South Korean offers stayed at the high end.
Southeast Asian players have mostly preferred to wait as prices were expected to fall further in the weeks ahead. “We’re not in a rush to replenish as we’ve enough stocks for another 1-2 months,” a Vietnamese converter said.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- Europe’s petchem plants close, assets change hands: How far has restructuring progressed?
- Suez recovery gains ground, but global shipping remains far from normal
- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?
