


Asian PS, ABS markets fail to sustain post-CNY spark despite cost pressures
by Merve Sezgün - msezgun@chemorbis.com

The PS and ABS markets in Asia returned from the Lunar New Year holiday a month ago amid firm sentiment, as players previously had high hopes of a fast demand recovery in China due to the government’s rapid shift away from its zero-Covid policy. However, that optimism has not lasted long. Although suppliers face cost pressures, the markets have yielded to poor demand in recent weeks.
PS sentiment falters after a firm start to post-holiday
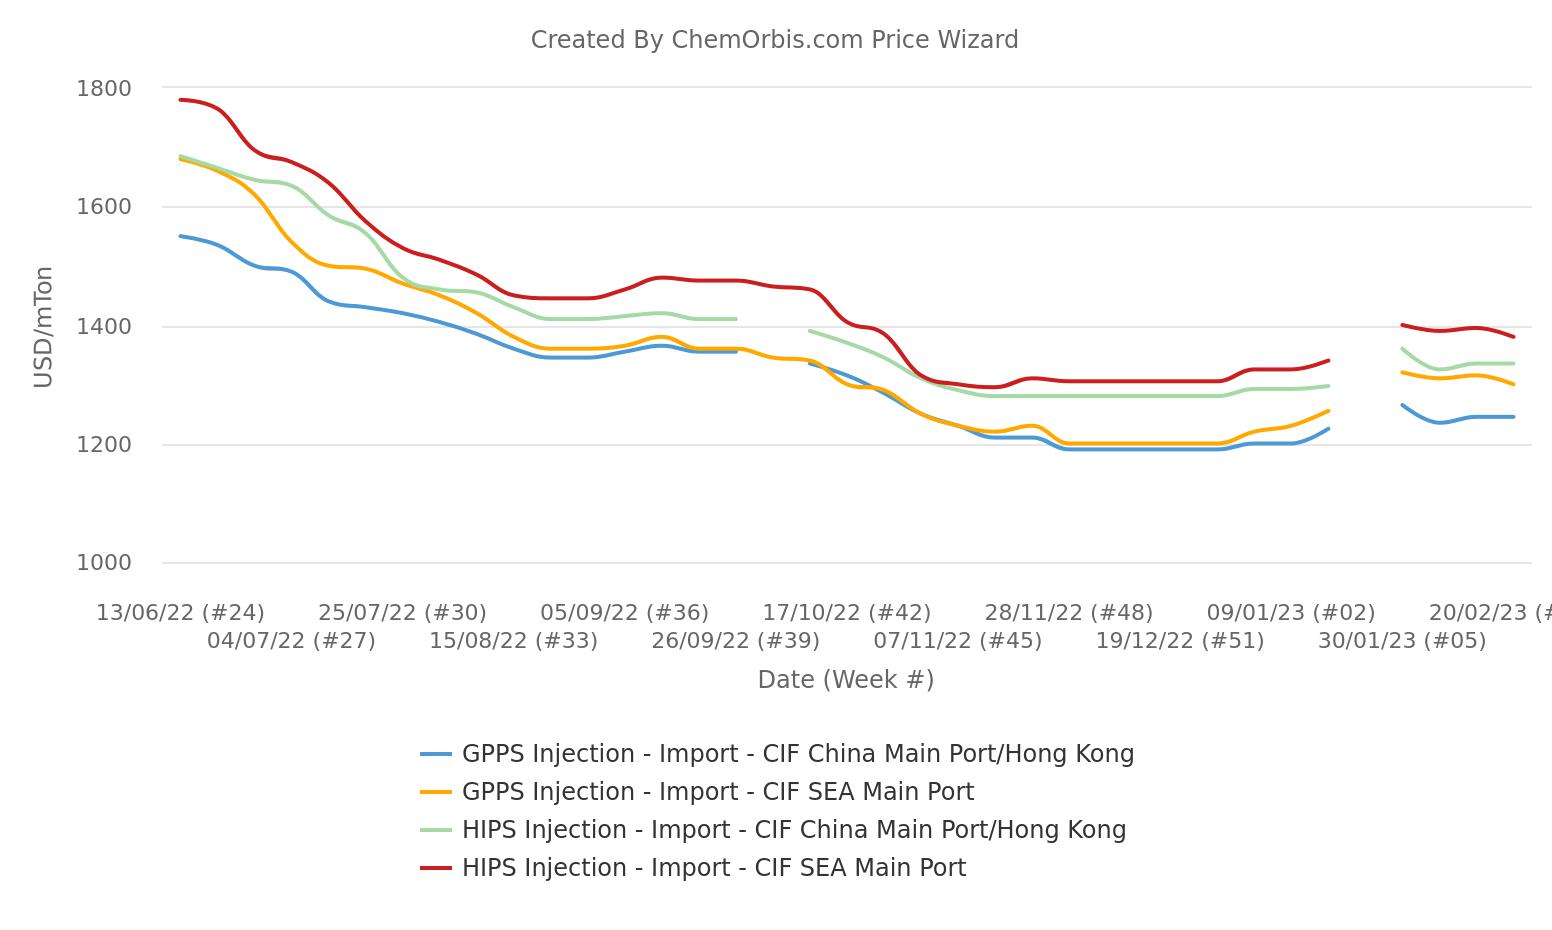
In the post-Lunar New Year week, GPPS and HIPS injection prices on CIF China/SEA basis were about 5-7% higher than their December lows, according to ChemOrbis Price Index data. Since then, however, the weekly averages of prices have erased some of their gains, as prices have tracked a stable to softer trend in the last three weeks.
Players across the region noted that the firm post-CNY sentiment faltered in the following weeks, as the demand recovery fell short of expectations. “Downstream buyers show strong resistance to any price hike attempts and prefer to deplete their inventories first,” noted a trader in China.
ABS scenery is similar to PS
ChemOrbis Price Index data suggest that CIF China/SEA ABS injection prices were also up by around 4-5% from the December lows in the first week after the holidays. As can be seen in the graph below, prices have tracked a mostly stable to slightly lower trajectory since then.
“Downstream demand recovery has been disappointing in China and Southeast Asia. Some converters procured sufficient stocks in the post-CNY week, however, buying ebbed again as of mid-February, as manufacturers refrained from extra purchases, feeling that there would be further price corrections. Supply is not an issue at the moment,” said a converter in Vietnam.

Suppliers lament cost pressure
While the markets are weighed on by reduced activity amid sluggish end-demand, suppliers of both PS and ABS across Asia lament the fact that they are struggling with high production costs.
“We are not able to reflect firm upstream values on ABS prices, as demand from downstream is calm. Buyers mostly make purchases when they are in need, and when they do, they place lower counterbids. For most ABS producers like us, dealing with low profit margins that require a few months to show any appreciable improvement, seems like a daunting task,” a source from a Southeast Asian producer said.
A Taiwanese PS producer maintained their offers last week, with a source from the producer also admitting, “It’s a quiet market, as the majority of players adopt a wait-and-see mode. Concluding deals at the current prices is a challenge, but we have no other choice given the cost pressure.”
In the upstream markets, spot styrene prices on CFR China basis were quoted at $1110/ton as of the end of last week. The latest level indicated a weekly gain of $20/ton, while it was up about 8% from late December. Spot butadiene prices with the same terms were at $1220/ton as of late last week, the highest level since July 2022, according to ChemOrbis Price Wizard. CFR China spot ACN prices were quoted at $1535/ton, up around 3% from a month earlier.
PS sentiment falters after a firm start to post-holiday
In the post-Lunar New Year week, GPPS and HIPS injection prices on CIF China/SEA basis were about 5-7% higher than their December lows, according to ChemOrbis Price Index data. Since then, however, the weekly averages of prices have erased some of their gains, as prices have tracked a stable to softer trend in the last three weeks.
Players across the region noted that the firm post-CNY sentiment faltered in the following weeks, as the demand recovery fell short of expectations. “Downstream buyers show strong resistance to any price hike attempts and prefer to deplete their inventories first,” noted a trader in China.
ABS scenery is similar to PS
ChemOrbis Price Index data suggest that CIF China/SEA ABS injection prices were also up by around 4-5% from the December lows in the first week after the holidays. As can be seen in the graph below, prices have tracked a mostly stable to slightly lower trajectory since then.
“Downstream demand recovery has been disappointing in China and Southeast Asia. Some converters procured sufficient stocks in the post-CNY week, however, buying ebbed again as of mid-February, as manufacturers refrained from extra purchases, feeling that there would be further price corrections. Supply is not an issue at the moment,” said a converter in Vietnam.
Suppliers lament cost pressure
While the markets are weighed on by reduced activity amid sluggish end-demand, suppliers of both PS and ABS across Asia lament the fact that they are struggling with high production costs.
“We are not able to reflect firm upstream values on ABS prices, as demand from downstream is calm. Buyers mostly make purchases when they are in need, and when they do, they place lower counterbids. For most ABS producers like us, dealing with low profit margins that require a few months to show any appreciable improvement, seems like a daunting task,” a source from a Southeast Asian producer said.
A Taiwanese PS producer maintained their offers last week, with a source from the producer also admitting, “It’s a quiet market, as the majority of players adopt a wait-and-see mode. Concluding deals at the current prices is a challenge, but we have no other choice given the cost pressure.”
In the upstream markets, spot styrene prices on CFR China basis were quoted at $1110/ton as of the end of last week. The latest level indicated a weekly gain of $20/ton, while it was up about 8% from late December. Spot butadiene prices with the same terms were at $1220/ton as of late last week, the highest level since July 2022, according to ChemOrbis Price Wizard. CFR China spot ACN prices were quoted at $1535/ton, up around 3% from a month earlier.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- After Germany and the Netherlands, Vynova files for bankruptcy in Belgium: Where do its remaining European operations stand?
- Oil price plunge rattles polymer markets: Will the rally lose steam?
- Naphtha rally intensifies in Europe, Asia; Europe hits highest since March 2022
- Europe’s petchem plants close, assets change hands: How far has restructuring progressed?
- Suez recovery gains ground, but global shipping remains far from normal
- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
