







Asian ethylene and propylene prices climb on short covering
by Jennifer Lee - jlee@chemorbis.com
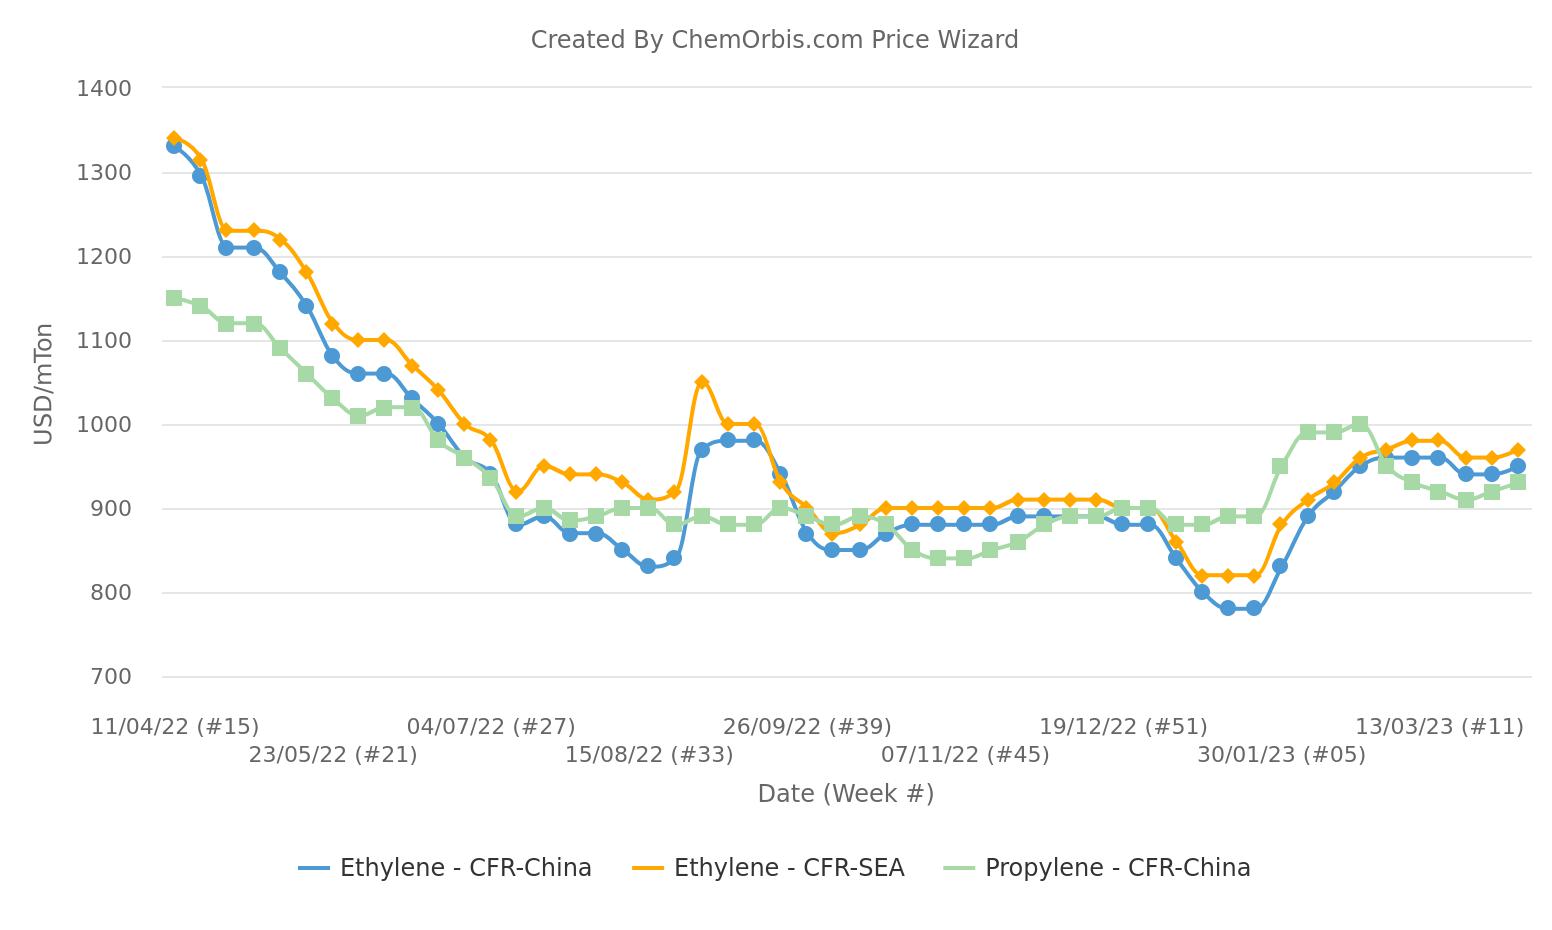
Asian ethylene and propylene prices have finally picked up momentum, following four weeks of an uneasy downtrend for propylene, and tenuous calmness for ethylene. This week, surprise cuts to the OPEC+ group’s output targets led to a strong rebound in crude oil futures, lifting market sentiment. Traders said the strong rebound in crude prices also led to quick short-covering by key traders who had previously offered lower priced ethylene and propylene spot cargoes to Chinese buyers for second-half April arrival.
There were reports that key traders bought ethylene at $950/ton CFR China and propylene at $930/ton CFR China for second half to late April delivery. Also aiding to boost sentiment is the start of more cracker turnarounds in Northeast Asia, across Japan, South Korea, and China. These Q2 turnarounds would help to tighten regional olefin supply, and place a floor on olefin prices, traders commented. Olefins prices had been under some pressure in the past few weeks due to several plants which had restarted from their Q1 planned maintenance shutdowns, as well as sluggish demand.
Additionally, the delayed start-up of China’s private-sector Sanjiang Fine Chemical’s 1 million tons/year ethylene cracker located at Jiaxing, Zhejiang from late March to May-June, or even into Q3, 2023 alleviated the pressure on China’s lengthening ethylene supply.
Spot ethylene prices edged up $10/ton from last week to be assessed at $950/ton CFR China and at $970/ton CFR Southeast Asia as of April 5. Spot propylene prices also edged up $10/ton from last week and were assessed at $930/ton CFR China and at $950/ton CFR Southeast Asia as of April 5.
South Korea’s major crackers will start planned turnarounds from April
Northeast Asia’s olefins supply which has lengthened due to the restart of several crackers, will again tighten from April onwards as more crackers start their scheduled maintenance turnarounds. Producers have also maintained cracker run rate cuts for extended periods although recent falling naphtha prices have led to slightly higher operating rates.
South Korea’s YNCC will likely start the planned maintenance turnaround at the 900,000 tons/year No 1 ethylene cracker in late April, according to industry sources. The Yeosu-based cracker will be shut for about 55 days, until late June. The producer has maintained reduced operating rates at its three Yeosu-based crackers at around 75-80%, according to industry sources. The crackers produce an estimated 2.3 million tons/year of ethylene and 1.15 million tons/year of propylene.
LG Chemical will commence its scheduled shutdown of the No 2 Yeosu-based naphtha cracker this week, according to traders. The No 2 cracker has a production capacity of 800,000 tons/year of ethylene and 400,000 tons/year of propylene. The turnaround will likely be extended into end-June, or longer, due to margin issues, the traders added. LG Chemical has three crackers located in Yeosu and Daesan, which produce around 3 million tons/year of ethylene.
Hanwha Total will also start the planned maintenance turnaround at the 1.4 million tons/year ethylene cracker in mid-April, according to industry sources. The Daesan-based cracker will be shut for 45 days, until end-May or early June.
“Major cracker operators across Northeast Asia and Southeast Asia will continue to minimise margin losses through a combination of reduced cracker run rates and turnarounds. When naphtha feedstock prices fall, there will be adjustments to run rates, since the cheaper production cost will lead to higher run rates. However, production will rebalance once olefins supply lengthens and prices are pressured again,” noted a Western trader.
There were reports that key traders bought ethylene at $950/ton CFR China and propylene at $930/ton CFR China for second half to late April delivery. Also aiding to boost sentiment is the start of more cracker turnarounds in Northeast Asia, across Japan, South Korea, and China. These Q2 turnarounds would help to tighten regional olefin supply, and place a floor on olefin prices, traders commented. Olefins prices had been under some pressure in the past few weeks due to several plants which had restarted from their Q1 planned maintenance shutdowns, as well as sluggish demand.
Additionally, the delayed start-up of China’s private-sector Sanjiang Fine Chemical’s 1 million tons/year ethylene cracker located at Jiaxing, Zhejiang from late March to May-June, or even into Q3, 2023 alleviated the pressure on China’s lengthening ethylene supply.
Spot ethylene prices edged up $10/ton from last week to be assessed at $950/ton CFR China and at $970/ton CFR Southeast Asia as of April 5. Spot propylene prices also edged up $10/ton from last week and were assessed at $930/ton CFR China and at $950/ton CFR Southeast Asia as of April 5.
South Korea’s major crackers will start planned turnarounds from April
Northeast Asia’s olefins supply which has lengthened due to the restart of several crackers, will again tighten from April onwards as more crackers start their scheduled maintenance turnarounds. Producers have also maintained cracker run rate cuts for extended periods although recent falling naphtha prices have led to slightly higher operating rates.
South Korea’s YNCC will likely start the planned maintenance turnaround at the 900,000 tons/year No 1 ethylene cracker in late April, according to industry sources. The Yeosu-based cracker will be shut for about 55 days, until late June. The producer has maintained reduced operating rates at its three Yeosu-based crackers at around 75-80%, according to industry sources. The crackers produce an estimated 2.3 million tons/year of ethylene and 1.15 million tons/year of propylene.
LG Chemical will commence its scheduled shutdown of the No 2 Yeosu-based naphtha cracker this week, according to traders. The No 2 cracker has a production capacity of 800,000 tons/year of ethylene and 400,000 tons/year of propylene. The turnaround will likely be extended into end-June, or longer, due to margin issues, the traders added. LG Chemical has three crackers located in Yeosu and Daesan, which produce around 3 million tons/year of ethylene.
Hanwha Total will also start the planned maintenance turnaround at the 1.4 million tons/year ethylene cracker in mid-April, according to industry sources. The Daesan-based cracker will be shut for 45 days, until end-May or early June.
“Major cracker operators across Northeast Asia and Southeast Asia will continue to minimise margin losses through a combination of reduced cracker run rates and turnarounds. When naphtha feedstock prices fall, there will be adjustments to run rates, since the cheaper production cost will lead to higher run rates. However, production will rebalance once olefins supply lengthens and prices are pressured again,” noted a Western trader.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- Europe’s petchem plants close, assets change hands: How far has restructuring progressed?
- Suez recovery gains ground, but global shipping remains far from normal
- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?

