







China import PE prices maintain supply-driven gains under shadow of local dynamics
by Pınar Polat - ppolat@chemorbis.com

Import PE prices in China have managed to extend gains into post-holiday period, although demand conditions have mostly remained slow. This is mainly due to tighter availability from the overseas markets, particularly from the Middle East, amid a series of maintenance shutdowns set for the February-March period in the region.
Local polyolefin run rates across China have also been cut for an extended period inside China as producers have been trying to keep supplies under control.
Adding to the supply limitations recently have been firmer spot ethylene feedstock prices, which have gained around 14% only within the last two weeks to reach at $890/ton CFR China, ChemOrbis Price Wizard suggests.
CIF PE prices test new highs
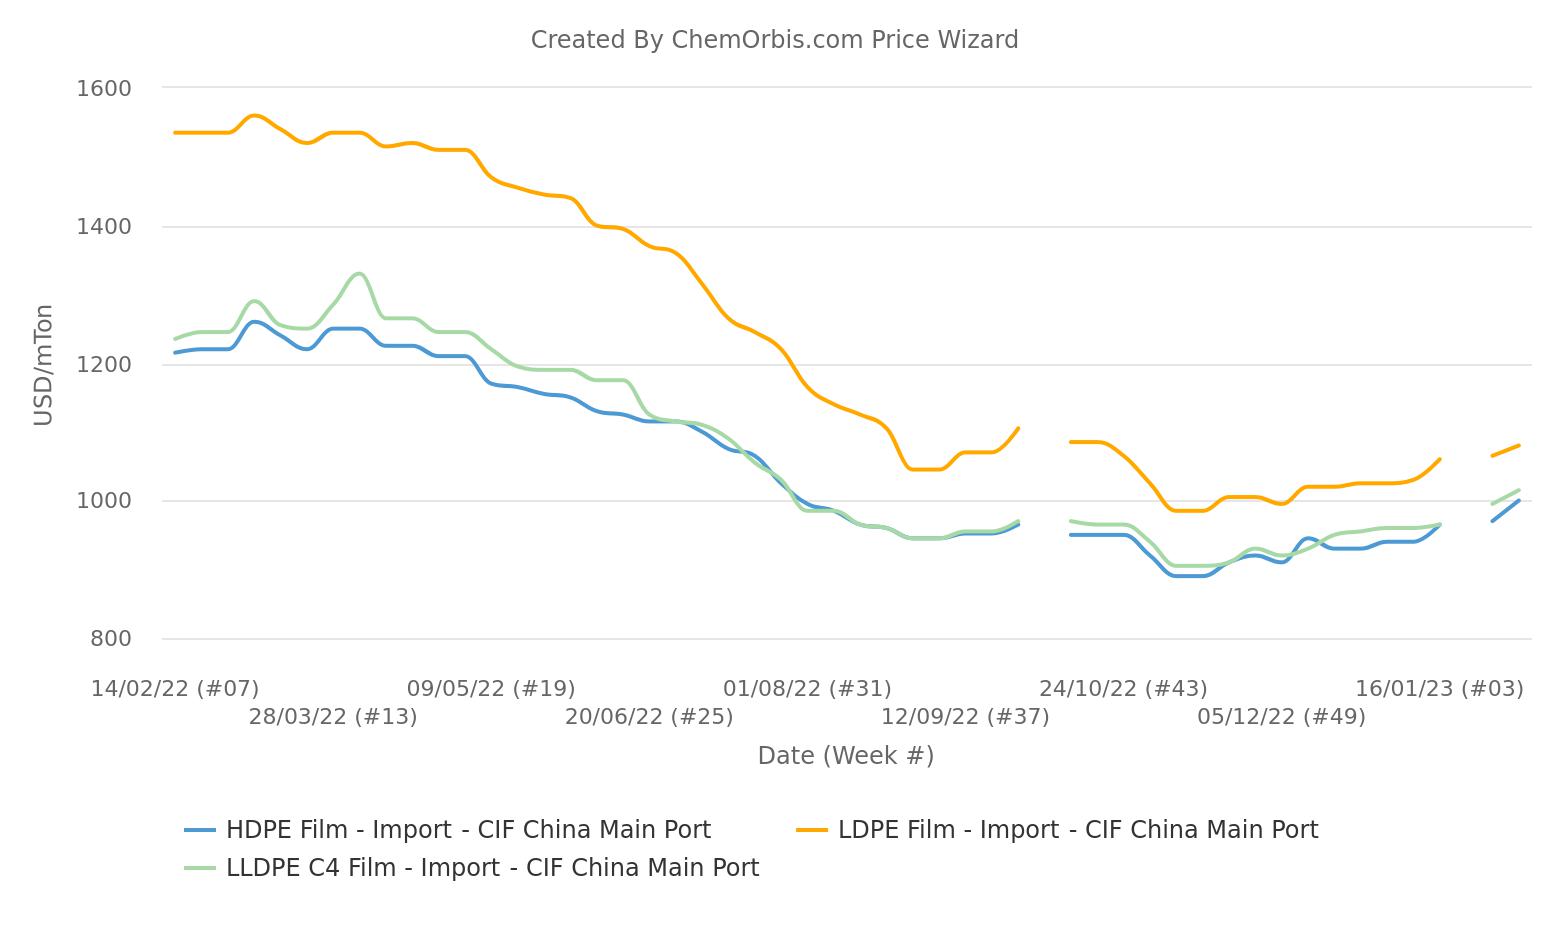
When compared to last week, import LDPE film prices were assessed $10-20/ton higher at $1050-1110/ton CIF China, cash basis. While the offers above $1100/ton CIF are present in the market again this week, the weekly average of LDPE has reached the highest level recorded since mid-October 2022, ChemOrbis data show.
Spot PE prices were also assessed $30/ton higher at $970-1030/ton for HDPE film and $20/ton higher at $980-1050/ton for LLDPE film, on similar terms. With offers above the $1000/ton CIF threshold appearing for both HDPE and LLDPE film, the weekly averages of these grades have also hit the highest levels seen since July 2022, ChemOrbis data suggest.
A trader commented, “Import PE offers have moved further up this week amid low supply. The storm in the US and the turnaround period in the Middle Eastern plants have resulted in supply limitations. After the holiday, demand has remained slow, but a recovery is expected by the middle of February.”
Concerns remain on local dynamics
Supply-driven bullishness on the sellers’ side is likely to underpin the sentiment, along with the country’s full re-opening after the strict Zero-Covid policy since December 2022, which has already been reflected in the economic data.
On the other hand, some players stick to their cautious stance considering the slow post-holiday demand recovery, the expected new PE capacities , as well as the weakness in Dalian futures prices.
Despite settling higher for the past two days, May LLDPE futures on the Dalian Commodity Exchange posted a weekly loss of CNY198/ton ($29/ton) as of February 9.
Finally, expectations of a demand recovery by the middle of February are being voiced by several players, and whether these expectations will materialize or not will also be determinant in terms of the sustainability of the current uptrend.
Local polyolefin run rates across China have also been cut for an extended period inside China as producers have been trying to keep supplies under control.
Adding to the supply limitations recently have been firmer spot ethylene feedstock prices, which have gained around 14% only within the last two weeks to reach at $890/ton CFR China, ChemOrbis Price Wizard suggests.
CIF PE prices test new highs
When compared to last week, import LDPE film prices were assessed $10-20/ton higher at $1050-1110/ton CIF China, cash basis. While the offers above $1100/ton CIF are present in the market again this week, the weekly average of LDPE has reached the highest level recorded since mid-October 2022, ChemOrbis data show.
Spot PE prices were also assessed $30/ton higher at $970-1030/ton for HDPE film and $20/ton higher at $980-1050/ton for LLDPE film, on similar terms. With offers above the $1000/ton CIF threshold appearing for both HDPE and LLDPE film, the weekly averages of these grades have also hit the highest levels seen since July 2022, ChemOrbis data suggest.
A trader commented, “Import PE offers have moved further up this week amid low supply. The storm in the US and the turnaround period in the Middle Eastern plants have resulted in supply limitations. After the holiday, demand has remained slow, but a recovery is expected by the middle of February.”
Concerns remain on local dynamics
Supply-driven bullishness on the sellers’ side is likely to underpin the sentiment, along with the country’s full re-opening after the strict Zero-Covid policy since December 2022, which has already been reflected in the economic data.
On the other hand, some players stick to their cautious stance considering the slow post-holiday demand recovery, the expected new PE capacities , as well as the weakness in Dalian futures prices.
Despite settling higher for the past two days, May LLDPE futures on the Dalian Commodity Exchange posted a weekly loss of CNY198/ton ($29/ton) as of February 9.
Finally, expectations of a demand recovery by the middle of February are being voiced by several players, and whether these expectations will materialize or not will also be determinant in terms of the sustainability of the current uptrend.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- Europe’s petchem plants close, assets change hands: How far has restructuring progressed?
- Suez recovery gains ground, but global shipping remains far from normal
- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?

