






China import PP, PE prices repel overseas sellers due to low netbacks
by Merve Sezgün - msezgun@chemorbis.com
China, the world’s largest polyolefin buyer, has been repelling overseas sellers recently as import PP and PE prices into the country have failed to catch up with the rising trend in other markets including Latin America, Africa, Turkey, and even Southeast Asia.
“Everybody is focused on the Latin America market due to attractive netbacks. Even Chinese PP suppliers are exporting to the region when they are able to find available containers,” players noted.
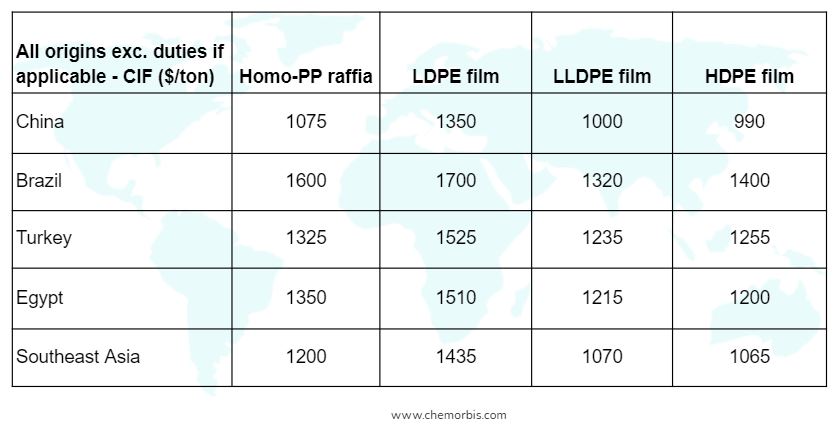
Currently, the South American market provides the highest netbacks for PP and PE sellers across the globe. As can be seen in the table below, there is a significant gap of $525/ton between CIF China and CIF Brazil homo-PP raffia prices. As for PE, the price gaps between the two markets are ranging from $320/ton to $410/ton.
Import prices into China were also standing visibly below the markets including Turkey, Egypt, and Southeast Asia at the time of publication. High freight rates and supply limitations have been supporting sellers’ successive hike requests in such markets, while the uptrend in China stalled at some point amid gradually declining appetite for import materials.
China stuck between limited import supply and approaching holiday lull
With the Lunar New Year holidays just around the corner (11-17 February), Chinese demand is waning and players do not expect the polyolefin markets to witness visible gains at least for the short term despite quite high prices in other countries.
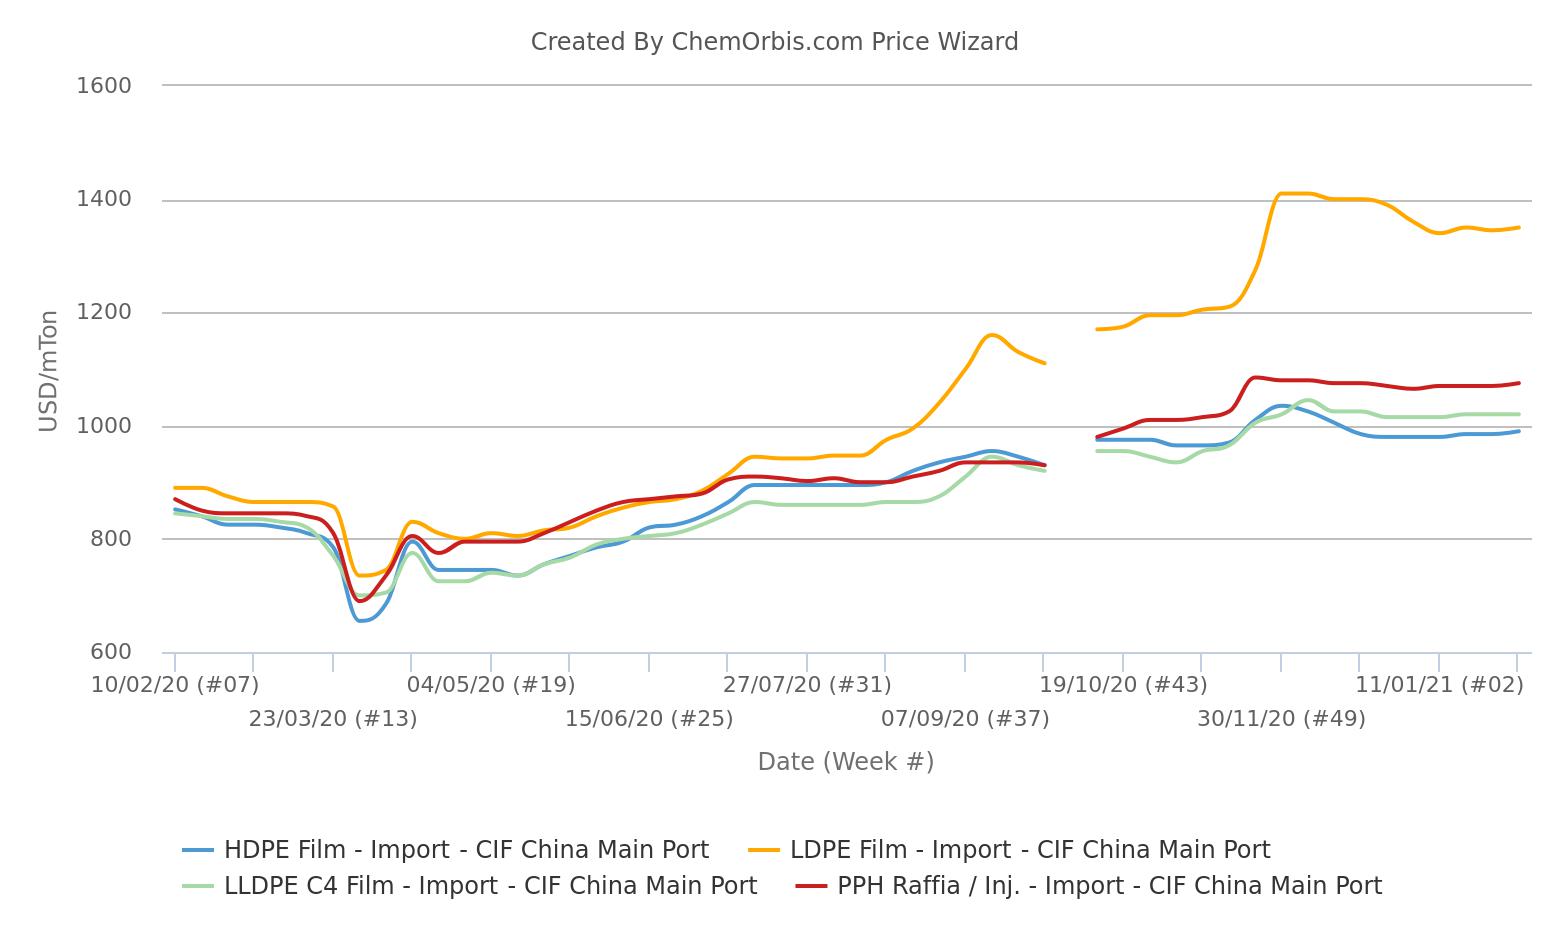
According to ChemOrbis Price Index data, import homo-PP raffia prices on CIF China basis have been largely hovering in a narrow range of $1065-1080/ton since late November.
PE prices have not seen any major changes either. LLDPE and HDPE film prices on CIF China basis have been tracking a largely stable trend for the past six weeks. LDPE film, meanwhile, more or less stabilized after seeing some downward corrections in December.
Saudi major announced slight hikes for Feb
A major Saudi Arabian producer lifted February prices to China by $10/ton for LLDPE, HDPE, and PP when compared to January. As for LDPE film, the producer applied $10-20/ton hikes on its new offers to the country. These slight hikes, however, have had limited impact on China’s import polyolefin markets so far.
The agent of the producer underlined that their allocation for February was quite limited.
“Overseas sellers are standing firm on their offers to China as they are not under any sales pressure. Most sellers are focused on other export outlets where juicy netbacks are achievable,” he said.
“Demand from China was weaker than our expectations in January due to rising COVID-19 cases as well as the approaching Lunar New Year holidays. Market activity has already slowed down with some players starting their holidays earlier than the official dates.
Hence hike amounts to China are quite small for February,” he added.
Better netbacks in other markets support post-holiday outlook
According to most players, China’s post-holiday polyolefin outlook is supported by a combination of overseas suppliers’ limited allocations and juicy netbacks in other export outlets.
“Due to attractive netbacks in several other markets, import supplies into China have tightened. Overseas PP and PE sellers are likely to adopt a firm stance on their offers to the country after the holidays,” a trader said.
Meanwhile, China’s polymer markets may not experience the traditional post-holiday lull this year since the government has been discouraging travel during the Lunar New Year holidays to prevent the spread of the virus.
“Downstream factories are likely to be able to resume operations right after the official holidays since millions of workers were told not to travel. Hence polyolefin demand from China may return earlier than expected this year. However, uncertainties remain due to the pandemic,” a few traders commented.
“Everybody is focused on the Latin America market due to attractive netbacks. Even Chinese PP suppliers are exporting to the region when they are able to find available containers,” players noted.
Currently, the South American market provides the highest netbacks for PP and PE sellers across the globe. As can be seen in the table below, there is a significant gap of $525/ton between CIF China and CIF Brazil homo-PP raffia prices. As for PE, the price gaps between the two markets are ranging from $320/ton to $410/ton.
Import prices into China were also standing visibly below the markets including Turkey, Egypt, and Southeast Asia at the time of publication. High freight rates and supply limitations have been supporting sellers’ successive hike requests in such markets, while the uptrend in China stalled at some point amid gradually declining appetite for import materials.
China stuck between limited import supply and approaching holiday lull
With the Lunar New Year holidays just around the corner (11-17 February), Chinese demand is waning and players do not expect the polyolefin markets to witness visible gains at least for the short term despite quite high prices in other countries.
According to ChemOrbis Price Index data, import homo-PP raffia prices on CIF China basis have been largely hovering in a narrow range of $1065-1080/ton since late November.
PE prices have not seen any major changes either. LLDPE and HDPE film prices on CIF China basis have been tracking a largely stable trend for the past six weeks. LDPE film, meanwhile, more or less stabilized after seeing some downward corrections in December.
Saudi major announced slight hikes for Feb
A major Saudi Arabian producer lifted February prices to China by $10/ton for LLDPE, HDPE, and PP when compared to January. As for LDPE film, the producer applied $10-20/ton hikes on its new offers to the country. These slight hikes, however, have had limited impact on China’s import polyolefin markets so far.
The agent of the producer underlined that their allocation for February was quite limited.
“Overseas sellers are standing firm on their offers to China as they are not under any sales pressure. Most sellers are focused on other export outlets where juicy netbacks are achievable,” he said.
“Demand from China was weaker than our expectations in January due to rising COVID-19 cases as well as the approaching Lunar New Year holidays. Market activity has already slowed down with some players starting their holidays earlier than the official dates.
Hence hike amounts to China are quite small for February,” he added.
Better netbacks in other markets support post-holiday outlook
According to most players, China’s post-holiday polyolefin outlook is supported by a combination of overseas suppliers’ limited allocations and juicy netbacks in other export outlets.
“Due to attractive netbacks in several other markets, import supplies into China have tightened. Overseas PP and PE sellers are likely to adopt a firm stance on their offers to the country after the holidays,” a trader said.
Meanwhile, China’s polymer markets may not experience the traditional post-holiday lull this year since the government has been discouraging travel during the Lunar New Year holidays to prevent the spread of the virus.
“Downstream factories are likely to be able to resume operations right after the official holidays since millions of workers were told not to travel. Hence polyolefin demand from China may return earlier than expected this year. However, uncertainties remain due to the pandemic,” a few traders commented.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?
- EU publishes tariff regulation, swings doors wide open to duty-free US plastics
- Stats: China rewrites PE trade dynamics as April exports explode amid Middle East disruptions
