







European PVC boosts premium over nosediving global markets
by Manolya Tufan - mtufan@chemorbis.com

July PVC deals have been wrapped up with mainly €50-80/ton drops in Europe, driven by rising availability and strong slowdown in demand. Higher production costs in Europe have kept the downtrend in check as PVC drops were milder than in other major markets. The PVC market now braces to recede for the fourth month in August given the global bearish run, lower costs and the summer holidays.
Producers point to energy costs
Regional suppliers were reluctant to cut their offers visibly, although activity shrank in the construction sector, which is the main driver of PVC demand. This was attributed to the energy-intensive nature of producing PVC amid unprecedentedly high gas and electricity costs.
According to a letter seen by ChemOrbis, Vynona informed its customers about the possibility of moving to monthly prices instead of quarterly prices and/or applying energy surcharges as the company’s chlor alkali production is hit by high electricity prices. Extreme volatility of the energy markets prevents the company from providing its customers with a stable, quarterly price.
Some regional producers have cut rates at their upstream and downstream units due to waning demand and higher utility requirements, with no confirmation at the time of writing.
Nevertheless, it is crucial to remind that overall supplies are rather comfortable amid a lack of major production issues within the bloc and more than usual import volumes.
Europe boosts premium as global markets plunge
As a result, European PVC markets saw moderate drops when compared with other global markets, where prices plunged to multi-year lows. Europe’s spot PVC K67-68 markets stand only 8% below their April peaks, while prices have receded to around a 4-month low on average.
Meanwhile, Taiwanese major’s sharp drops for August exacerbated the bearish run in Asian PVC markets. PVC K67-68 prices on CIF China and SEA basis broke below the $1000/ton level, hitting their lowest levels since September 2020. Prices on CIF India basis and non-dutiable origins on CIF Turkey basis were also the lowest since that time.
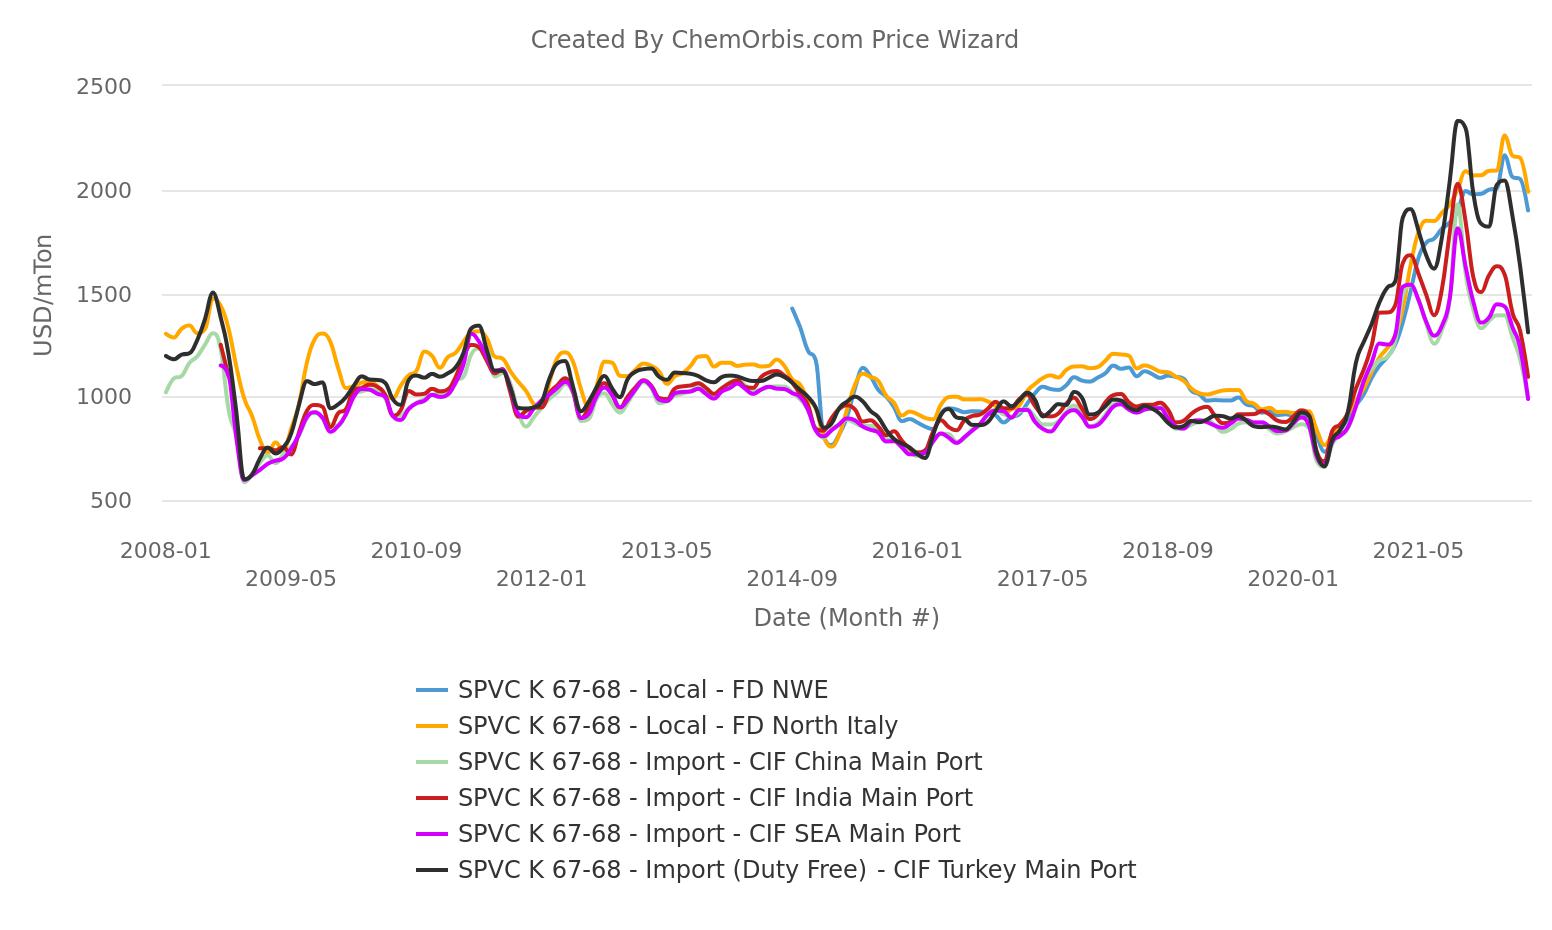
This widened the gap between Europe and other markets. Indeed, Europe’s premium reached fresh highs over China ($957/ton), Southeast Asia ($982/ton), India ($842/ton) and Turkey ($667/ton) in the week ending July 22.
Imports see little interest
Despite juicy netbacks in Europe, import suppliers have been unable to boost their PVC exports to the continent significantly. This coincided with a sharp slowdown in demand and hesitant trading towards import cargoes amid widespread uncertainties.
Aug PVC prices likely to fall
Ethylene contracts are expected to settle with around €70/ton decreases for August. This, coupled with the summer lull and global bearishness, triggers expectations for further softening in European PVC markets. However, suppliers’ stance amid high utility costs may keep a potential softening in check.
Producers point to energy costs
Regional suppliers were reluctant to cut their offers visibly, although activity shrank in the construction sector, which is the main driver of PVC demand. This was attributed to the energy-intensive nature of producing PVC amid unprecedentedly high gas and electricity costs.
According to a letter seen by ChemOrbis, Vynona informed its customers about the possibility of moving to monthly prices instead of quarterly prices and/or applying energy surcharges as the company’s chlor alkali production is hit by high electricity prices. Extreme volatility of the energy markets prevents the company from providing its customers with a stable, quarterly price.
Some regional producers have cut rates at their upstream and downstream units due to waning demand and higher utility requirements, with no confirmation at the time of writing.
Nevertheless, it is crucial to remind that overall supplies are rather comfortable amid a lack of major production issues within the bloc and more than usual import volumes.
Europe boosts premium as global markets plunge
As a result, European PVC markets saw moderate drops when compared with other global markets, where prices plunged to multi-year lows. Europe’s spot PVC K67-68 markets stand only 8% below their April peaks, while prices have receded to around a 4-month low on average.
Meanwhile, Taiwanese major’s sharp drops for August exacerbated the bearish run in Asian PVC markets. PVC K67-68 prices on CIF China and SEA basis broke below the $1000/ton level, hitting their lowest levels since September 2020. Prices on CIF India basis and non-dutiable origins on CIF Turkey basis were also the lowest since that time.
This widened the gap between Europe and other markets. Indeed, Europe’s premium reached fresh highs over China ($957/ton), Southeast Asia ($982/ton), India ($842/ton) and Turkey ($667/ton) in the week ending July 22.
Imports see little interest
Despite juicy netbacks in Europe, import suppliers have been unable to boost their PVC exports to the continent significantly. This coincided with a sharp slowdown in demand and hesitant trading towards import cargoes amid widespread uncertainties.
Aug PVC prices likely to fall
Ethylene contracts are expected to settle with around €70/ton decreases for August. This, coupled with the summer lull and global bearishness, triggers expectations for further softening in European PVC markets. However, suppliers’ stance amid high utility costs may keep a potential softening in check.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- Europe’s petchem plants close, assets change hands: How far has restructuring progressed?
- Suez recovery gains ground, but global shipping remains far from normal
- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?

