







SE Asia PP, PE markets succumb to renewed demand pressure, all eyes on China’s return
by Pınar Polat - ppolat@chemorbis.com
Having edged up by mid-September with support from tighter availability after a 6-month downturn, import PP and PE markets across Southeast Asia turned stable to soft again this past week. This is because demand has regained prominance amid the absence of China, who is returning from a week-long National Day holiday today.
Weaker local currencies against the USD and recession fears have also put further pressure on the demand front, making business difficult particularly for import cargoes throughout the region.
PP hike attempts see stiff resistance
In Southeast Asia PP markets, sellers attempted to hike prices but were resisted by buyers citing the persistently weak demand.
“We don’t have a lot of material to offer currently. We’ll remain on the sidelines, waiting for the opportune moment to buy. Feedstock prices have been stable despite rising crude oil prices,” said a trader in Vietnam.
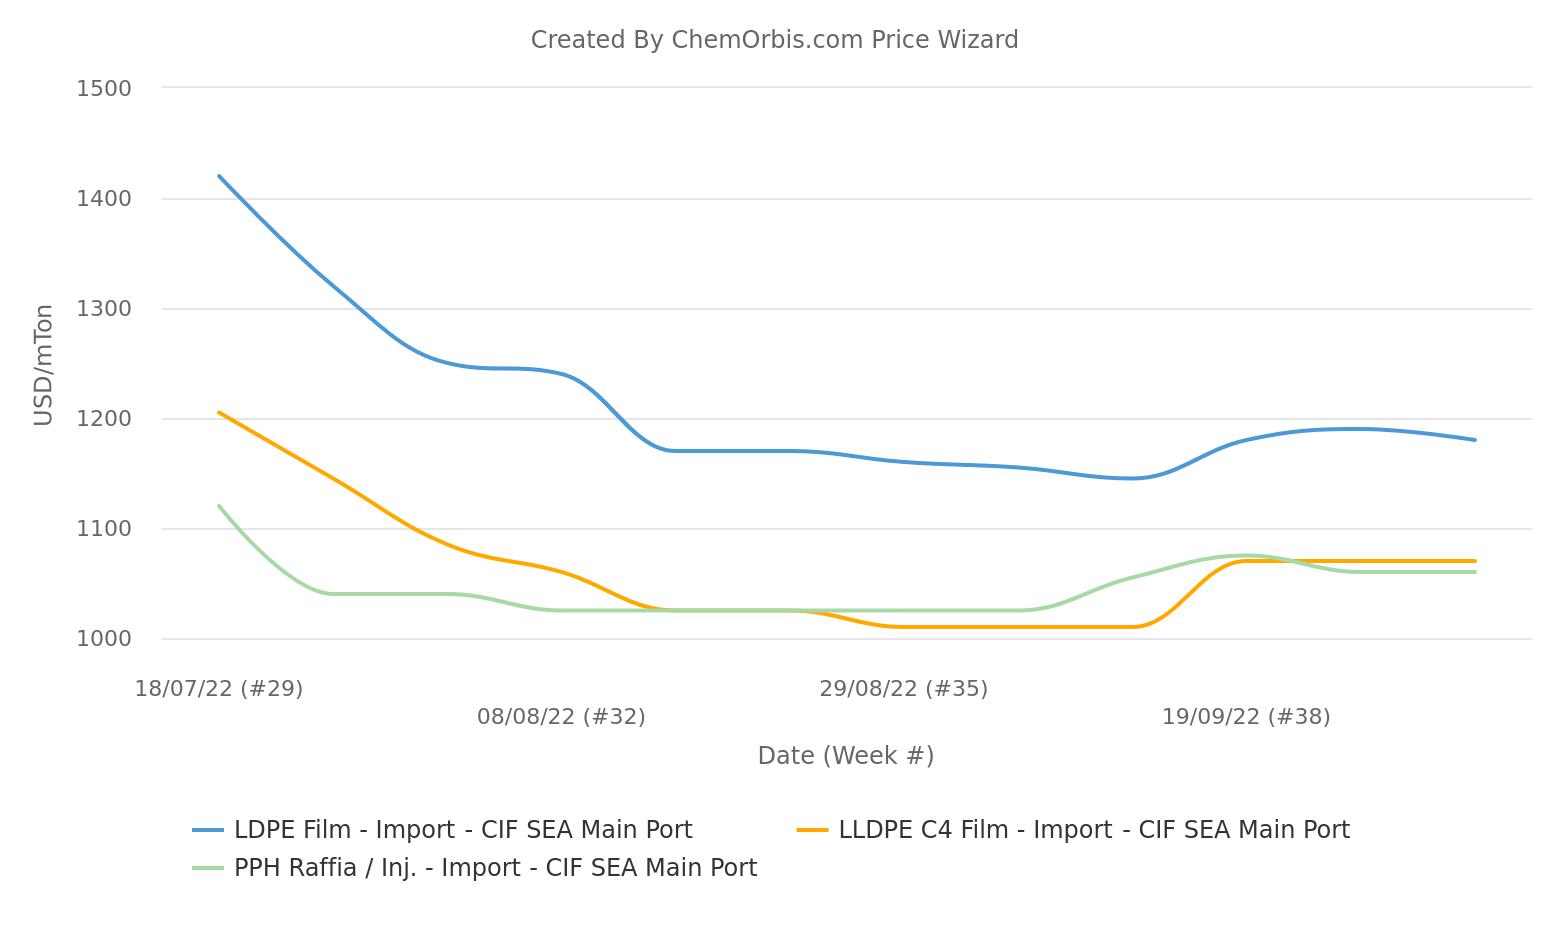
During the week that ended on October 7, import homo-PP raffia and inj. prices for all origins were assessed stable at $1010-1110/ton CIF Southeast Asia, cash.
PE reverses course after two weeks of stable to firmer trend
In Southeast Asia PE markets, PE prices yielded to slow demand, and lower feedstock ethylene prices after following a stable to firmer trend for two weeks.
“Overall demand remains weak. Buyers are careful and hesitant with any attempt to raise prices. Weak demand for end products is the main factor for the slow market. It could be even worse as we approach the year-end, with recessionary pressures setting in,” an agent in the region of a major Middle East producer said.
During the week that ended on October 7, import PE film prices for all origins were assessed $10/ton lower week-over-week at $1140-1220/ton CIF, cash for LDPE film. HDPE film was assessed stable to $10/ton lower at $1030-1100/ton while LLDPE film prices were also assessed stable week-over-week at $1030-1110/ton CIF with the same terms.
Players discuss post-holiday trend in China
PP prices were steady in China in the week before the National Day holidays while PE prices were firmer. Improving demand with “the Golden September Silver October season” as well as limited overseas supply amid turnarounds were cited as factors supporting the sentiment.
Regarding the post-holiday period, expectations are closely tied to demand again.
“Sentiment in China PE, and PP markets are expected to stay firm for the post-holiday term so long as demand conditions continue to improve. We are optimistic about the China polyolefins outlook but it’s a cautious optimism given global inflation and economic slowdown as well as various pandemic lockdowns across China,” a trader said.
Another trader commented, “We think China prices will go up after the holiday due to firmer crude. But still, price increases are likely to be limited, depending on the status of China’s Covid-19 prevention policy. If the government sticks with its zero-case policy after the Communist Party conference on October 16, then the sentiment may weaken.”
On a side note, an accumulation in the local supply during the holiday is a factor to watch. China’s two major domestic producers’ combined PE and PP inventories were standing at 575,000 tons as of September 30.
Weaker local currencies against the USD and recession fears have also put further pressure on the demand front, making business difficult particularly for import cargoes throughout the region.
PP hike attempts see stiff resistance
In Southeast Asia PP markets, sellers attempted to hike prices but were resisted by buyers citing the persistently weak demand.
“We don’t have a lot of material to offer currently. We’ll remain on the sidelines, waiting for the opportune moment to buy. Feedstock prices have been stable despite rising crude oil prices,” said a trader in Vietnam.
During the week that ended on October 7, import homo-PP raffia and inj. prices for all origins were assessed stable at $1010-1110/ton CIF Southeast Asia, cash.
PE reverses course after two weeks of stable to firmer trend
In Southeast Asia PE markets, PE prices yielded to slow demand, and lower feedstock ethylene prices after following a stable to firmer trend for two weeks.
“Overall demand remains weak. Buyers are careful and hesitant with any attempt to raise prices. Weak demand for end products is the main factor for the slow market. It could be even worse as we approach the year-end, with recessionary pressures setting in,” an agent in the region of a major Middle East producer said.
During the week that ended on October 7, import PE film prices for all origins were assessed $10/ton lower week-over-week at $1140-1220/ton CIF, cash for LDPE film. HDPE film was assessed stable to $10/ton lower at $1030-1100/ton while LLDPE film prices were also assessed stable week-over-week at $1030-1110/ton CIF with the same terms.
Players discuss post-holiday trend in China
PP prices were steady in China in the week before the National Day holidays while PE prices were firmer. Improving demand with “the Golden September Silver October season” as well as limited overseas supply amid turnarounds were cited as factors supporting the sentiment.
Regarding the post-holiday period, expectations are closely tied to demand again.
“Sentiment in China PE, and PP markets are expected to stay firm for the post-holiday term so long as demand conditions continue to improve. We are optimistic about the China polyolefins outlook but it’s a cautious optimism given global inflation and economic slowdown as well as various pandemic lockdowns across China,” a trader said.
Another trader commented, “We think China prices will go up after the holiday due to firmer crude. But still, price increases are likely to be limited, depending on the status of China’s Covid-19 prevention policy. If the government sticks with its zero-case policy after the Communist Party conference on October 16, then the sentiment may weaken.”
On a side note, an accumulation in the local supply during the holiday is a factor to watch. China’s two major domestic producers’ combined PE and PP inventories were standing at 575,000 tons as of September 30.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- Europe’s petchem plants close, assets change hands: How far has restructuring progressed?
- Suez recovery gains ground, but global shipping remains far from normal
- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?

