






Will Asia’s PS markets follow ABS higher on cost support?
by Merve Madakbaşı - mmadakbasi@chemorbis.com

ABS sellers in China and Southeast Asia were encouraged enough to lift their offers slightly over the past week. The main factors that propelled the market higher were the rebound in crude oil futures as well as improved end users’ demand.
Nonetheless, PS was unfazed by crude’s firming, while it remains to be seen whether or not the product will be propped up by the styrene gains this week.
Import ABS was underpinned by low supply, bouncing crude
The recovery in Asian ABS markets came in line with tight supply in China as well as improved end users’ demand.
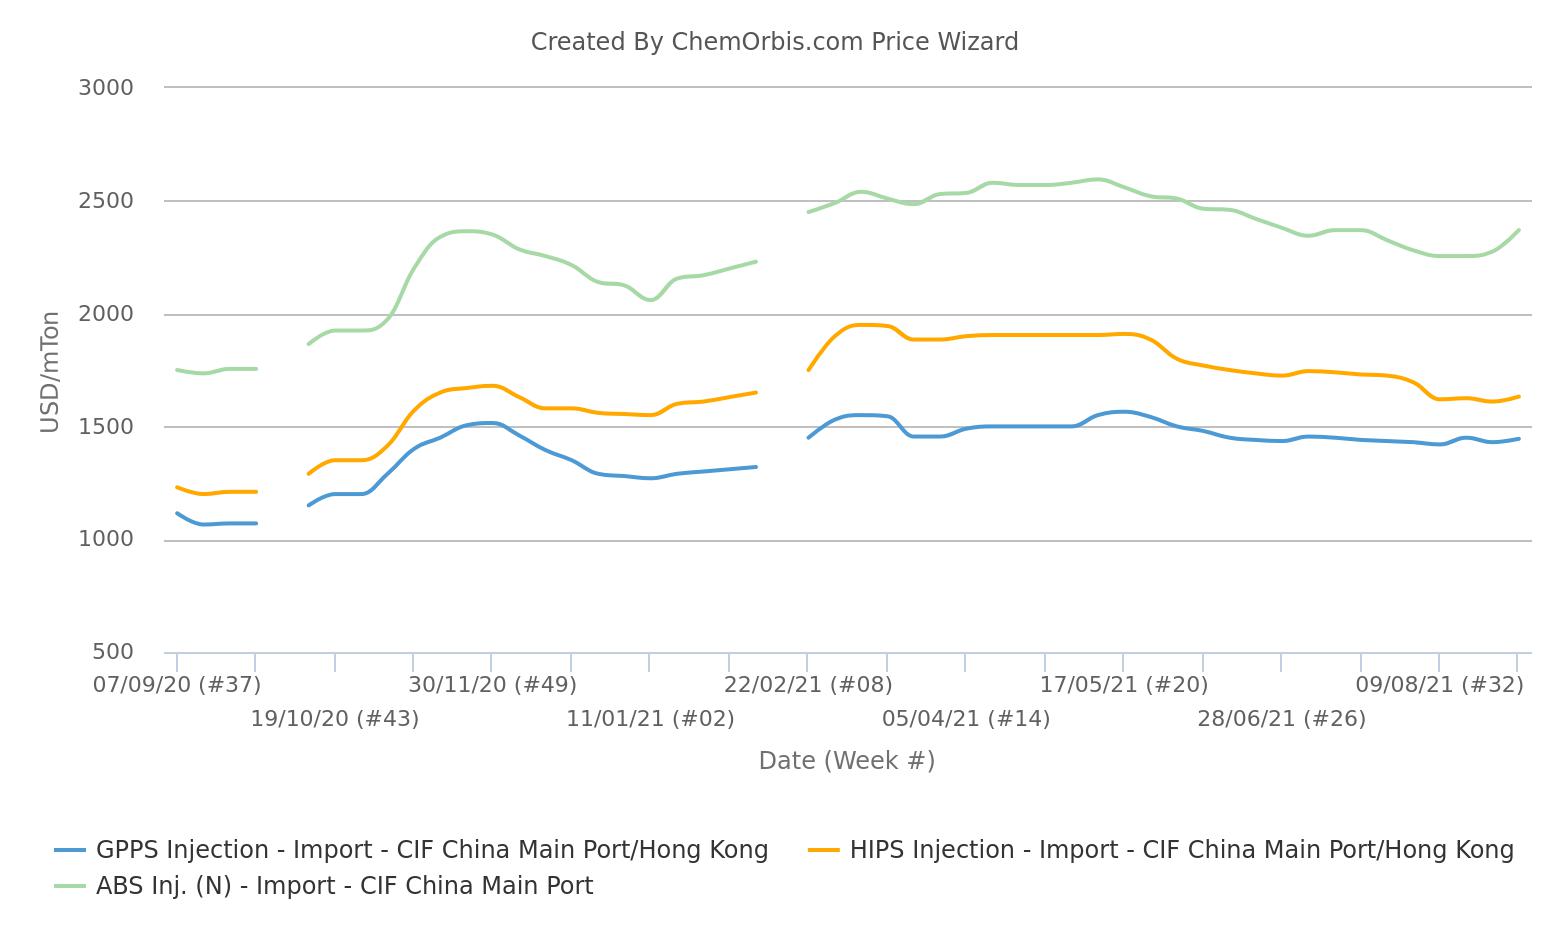
Import ABS inj. prices for overall origins rose $10-30/ton to be assessed at $2240-2310/ton CIF China, cash at the end of last week. The market was also affected by reduced local supplies due to plant turnarounds in East and Northeast China.
Chinese Shandong Hai Jiang and Liaodong Hua Gong are currently undergoing maintenance turnarounds, while Liaoning Petrochemical’s plant restart will be delayed until September. Ningbo LG Yongxing will also conduct planned maintenance in September.
Import offers to Southeast Asia followed suit despite the virus-hit demand scene given the curfews in Thailand, Malaysia, Indonesia, and the Philippines. ABS inj. was assessed slightly higher at $2270-2330/ton CIF SEA, cash as of the end of last week.
Overall, the markets were bolstered by a higher energy complex, where WTI (NYMEX) futures traded near $69/bbl during an intraday session on Monday after closing higher on Friday.
Disrupted oil production in the US Gulf Coast may hold the market elevated over the near term, which may support downstream benzene and styrene markets, according to some players.
Yet, PS was pervaded by lackluster derivative demand
The PS market was unresponsive to firmer energy costs and recovering ABS markets in the region, however. The main factor that dimmed the sentiment was the discouraging demand from downstream buyers.
“Purchases were mostly hand-to-mouth as end demand remained stalled by late August. It remains to be seen whether or not PS will respond to improved sentiment for other styrenics in early September,” said a player as of late last week.
On Monday, a China-based trader said to ChemOrbis: "Suppliers are trying to remain adamant about their firm prices. However, prices at the high ends of the market continue to see resistance. The market may fluctuate within a narrow range in the short term unless costs continue to climb more visibly."
Spot styrene gained further ground on Monday
The spot styrene market closed last week on a firm footing, bolstered by the recent rebound in the energy complex. At the end of last week, prices indicated $20/ton gains from the previous week both on CFR China and FOB Korea basis.
Plus, spot benzene and styrene prices edged up further on Monday as the news that petrochemical hubs in Louisiana, the US, were hit by Hurricane Ida on Sunday. This caused some jitters among players about reduced styrene supplies into Asia for the coming term.
Nonetheless, PS was unfazed by crude’s firming, while it remains to be seen whether or not the product will be propped up by the styrene gains this week.
Import ABS was underpinned by low supply, bouncing crude
The recovery in Asian ABS markets came in line with tight supply in China as well as improved end users’ demand.
Import ABS inj. prices for overall origins rose $10-30/ton to be assessed at $2240-2310/ton CIF China, cash at the end of last week. The market was also affected by reduced local supplies due to plant turnarounds in East and Northeast China.
Chinese Shandong Hai Jiang and Liaodong Hua Gong are currently undergoing maintenance turnarounds, while Liaoning Petrochemical’s plant restart will be delayed until September. Ningbo LG Yongxing will also conduct planned maintenance in September.
Import offers to Southeast Asia followed suit despite the virus-hit demand scene given the curfews in Thailand, Malaysia, Indonesia, and the Philippines. ABS inj. was assessed slightly higher at $2270-2330/ton CIF SEA, cash as of the end of last week.
Overall, the markets were bolstered by a higher energy complex, where WTI (NYMEX) futures traded near $69/bbl during an intraday session on Monday after closing higher on Friday.
Disrupted oil production in the US Gulf Coast may hold the market elevated over the near term, which may support downstream benzene and styrene markets, according to some players.
Yet, PS was pervaded by lackluster derivative demand
The PS market was unresponsive to firmer energy costs and recovering ABS markets in the region, however. The main factor that dimmed the sentiment was the discouraging demand from downstream buyers.
“Purchases were mostly hand-to-mouth as end demand remained stalled by late August. It remains to be seen whether or not PS will respond to improved sentiment for other styrenics in early September,” said a player as of late last week.
On Monday, a China-based trader said to ChemOrbis: "Suppliers are trying to remain adamant about their firm prices. However, prices at the high ends of the market continue to see resistance. The market may fluctuate within a narrow range in the short term unless costs continue to climb more visibly."
Spot styrene gained further ground on Monday
The spot styrene market closed last week on a firm footing, bolstered by the recent rebound in the energy complex. At the end of last week, prices indicated $20/ton gains from the previous week both on CFR China and FOB Korea basis.
Plus, spot benzene and styrene prices edged up further on Monday as the news that petrochemical hubs in Louisiana, the US, were hit by Hurricane Ida on Sunday. This caused some jitters among players about reduced styrene supplies into Asia for the coming term.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?
- EU publishes tariff regulation, swings doors wide open to duty-free US plastics
- Stats: China rewrites PE trade dynamics as April exports explode amid Middle East disruptions
- Role reversal: Iran seeks polymers from Türkiye amid war disruptions
- US PE cracks after record highs; corrections spread from Asia to Europe and Türkiye
