

China’s booming PP exports redraw Asia trade map amid structural surplus
by Merve Sezgün - msezgun@chemorbis.com
China’s record polypropylene exports during the first half of 2026 may have grabbed the headlines, but the real story lies beneath the customs data. The surge in overseas shipments was not simply the result of temporary arbitrage opportunities created by supply disruptions in the Middle East. Instead, it highlighted a structural shift that has been building for years as China’s production capacity has expanded much faster than domestic consumption.
According to ChemOrbis Supply Wizard, China added nearly 20 million tons/year of polypropylene capacity between 2021 and 2025. More than 5 million tons/year is scheduled to come online in 2026, followed by another nearly 5 million tons/year in 2027.
This means that even after exports potentially exceed 5 million tons this year, the country’s production surplus is still likely to grow further.
Capacity growth has outpaced demand
China’s domestic PP industry has expanded at one of the fastest rates seen anywhere in the global petrochemical sector. Yet demand has failed to keep pace. The prolonged weakness in the property sector, cautious consumer spending and slower growth across several downstream manufacturing industries have all limited domestic polymer consumption.
As a result, the country’s rapidly growing production base increasingly requires overseas markets to absorb surplus material.
Exporting has therefore evolved from an attractive commercial opportunity into an operational necessity for many producers.
A diversified feedstock base strengthens China’s competitive position
China’s competitiveness is not built solely on scale. Unlike many producers elsewhere in Asia, the country operates one of the world’s most diversified polypropylene production systems.
Alongside conventional naphtha-based plants, China has invested heavily in coal-to-olefins (CTO), methanol-to-olefins (MTO), propane dehydrogenation (PDH) and other alternative production routes.
Not every Chinese producer operates at the bottom of the global cost curve, particularly during periods of weak margins or low operating rates. However, the diversity of feedstocks reduces dependence on any single raw material or import route while giving producers greater flexibility during periods of geopolitical uncertainty or feedstock volatility.
That flexibility becomes increasingly valuable whenever global supply chains are disrupted.
The Middle East disruptions revealed China’s export capability
The supply disruptions that affected Middle Eastern producers during the second quarter of 2026 did not create China’s export expansion. They accelerated it.
As availability from several traditional suppliers tightened, Chinese producers rapidly increased shipments into markets that had previously relied more heavily on Middle Eastern cargoes.
The episode demonstrated not only that China possessed sufficient surplus volumes, but also that it had already developed the commercial relationships, logistics and export channels required to place large quantities of material overseas within a relatively short period.
Perhaps more importantly, exports remained historically high even after Middle Eastern supply conditions improved during June. That suggests the disruptions exposed an export capability that already existed rather than creating a temporary export boom.
Traditional suppliers now face competition on two fronts
China’s changing role has created a new competitive landscape across Asia. Historically, exporters from South Korea, Singapore, Taiwan and the Middle East viewed China as one of their largest and most reliable destinations. That market is steadily shrinking.
At the same time, Chinese producers are increasingly competing in many of those same export markets. The result is a growing displacement effect. Cargoes that previously moved into China must now find alternative destinations, while Chinese material is simultaneously expanding into those very markets with increasingly competitive offers. Rather than replacing one supplier, China is adding another major source of supply into an already well-supplied regional market.
Southeast Asia emerges as the key battleground
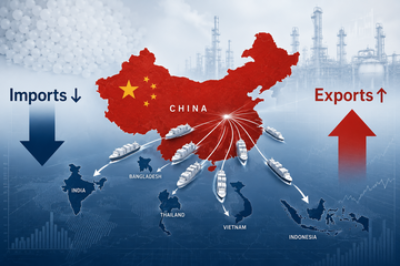
Few regions illustrate this competitive shift more clearly than Southeast Asia. Vietnam, Indonesia and Thailand remain structurally dependent on imported polypropylene while enjoying relatively short shipping distances from China. These markets have therefore become natural outlets for China’s expanding surplus.
Chinese producers have also become increasingly capable of responding quickly whenever traditional suppliers experience production outages, logistical constraints or geopolitical disruptions.
As Chinese participation grows, producers from Northeast Asia, the Middle East and ASEAN are finding themselves competing more directly for the same customers. Competition is therefore becoming broader rather than simply more intense.
India is becoming strategically more important
India is emerging as another market of growing strategic importance. China’s share of exports destined for India increased significantly during the first half of 2026 as buyers sought alternative supply during disruptions affecting Gulf producers.
The experience demonstrated that China is increasingly capable of serving a market traditionally dominated by Middle Eastern suppliers whenever commercial conditions become favorable.
As China’s export infrastructure continues to mature, India is likely to become a more regular destination rather than simply an opportunistic outlet.
A new era for Asia’s PP market
China’s emergence as a structural PP exporter represents far more than another record in customs statistics.It marks a fundamental rebalancing of the Asian PP market.
For decades, China was the world’s largest destination for imported resin. Increasingly, it is becoming the supplier that shapes regional trade flows instead.
With another 10 million tons/year of new capacity scheduled for 2026-2027, the country’s export surplus appears set to remain a defining feature of the Asian PP market for years to come.
According to ChemOrbis Supply Wizard, China added nearly 20 million tons/year of polypropylene capacity between 2021 and 2025. More than 5 million tons/year is scheduled to come online in 2026, followed by another nearly 5 million tons/year in 2027.
This means that even after exports potentially exceed 5 million tons this year, the country’s production surplus is still likely to grow further.
Capacity growth has outpaced demand
China’s domestic PP industry has expanded at one of the fastest rates seen anywhere in the global petrochemical sector. Yet demand has failed to keep pace. The prolonged weakness in the property sector, cautious consumer spending and slower growth across several downstream manufacturing industries have all limited domestic polymer consumption.
As a result, the country’s rapidly growing production base increasingly requires overseas markets to absorb surplus material.
Exporting has therefore evolved from an attractive commercial opportunity into an operational necessity for many producers.
A diversified feedstock base strengthens China’s competitive position
China’s competitiveness is not built solely on scale. Unlike many producers elsewhere in Asia, the country operates one of the world’s most diversified polypropylene production systems.
Alongside conventional naphtha-based plants, China has invested heavily in coal-to-olefins (CTO), methanol-to-olefins (MTO), propane dehydrogenation (PDH) and other alternative production routes.
Not every Chinese producer operates at the bottom of the global cost curve, particularly during periods of weak margins or low operating rates. However, the diversity of feedstocks reduces dependence on any single raw material or import route while giving producers greater flexibility during periods of geopolitical uncertainty or feedstock volatility.
That flexibility becomes increasingly valuable whenever global supply chains are disrupted.
The Middle East disruptions revealed China’s export capability
The supply disruptions that affected Middle Eastern producers during the second quarter of 2026 did not create China’s export expansion. They accelerated it.
As availability from several traditional suppliers tightened, Chinese producers rapidly increased shipments into markets that had previously relied more heavily on Middle Eastern cargoes.
The episode demonstrated not only that China possessed sufficient surplus volumes, but also that it had already developed the commercial relationships, logistics and export channels required to place large quantities of material overseas within a relatively short period.
Perhaps more importantly, exports remained historically high even after Middle Eastern supply conditions improved during June. That suggests the disruptions exposed an export capability that already existed rather than creating a temporary export boom.
Traditional suppliers now face competition on two fronts
China’s changing role has created a new competitive landscape across Asia. Historically, exporters from South Korea, Singapore, Taiwan and the Middle East viewed China as one of their largest and most reliable destinations. That market is steadily shrinking.
At the same time, Chinese producers are increasingly competing in many of those same export markets. The result is a growing displacement effect. Cargoes that previously moved into China must now find alternative destinations, while Chinese material is simultaneously expanding into those very markets with increasingly competitive offers. Rather than replacing one supplier, China is adding another major source of supply into an already well-supplied regional market.
Southeast Asia emerges as the key battleground
Few regions illustrate this competitive shift more clearly than Southeast Asia. Vietnam, Indonesia and Thailand remain structurally dependent on imported polypropylene while enjoying relatively short shipping distances from China. These markets have therefore become natural outlets for China’s expanding surplus.
Chinese producers have also become increasingly capable of responding quickly whenever traditional suppliers experience production outages, logistical constraints or geopolitical disruptions.
As Chinese participation grows, producers from Northeast Asia, the Middle East and ASEAN are finding themselves competing more directly for the same customers. Competition is therefore becoming broader rather than simply more intense.
India is becoming strategically more important
India is emerging as another market of growing strategic importance. China’s share of exports destined for India increased significantly during the first half of 2026 as buyers sought alternative supply during disruptions affecting Gulf producers.
The experience demonstrated that China is increasingly capable of serving a market traditionally dominated by Middle Eastern suppliers whenever commercial conditions become favorable.
As China’s export infrastructure continues to mature, India is likely to become a more regular destination rather than simply an opportunistic outlet.
A new era for Asia’s PP market
China’s emergence as a structural PP exporter represents far more than another record in customs statistics.It marks a fundamental rebalancing of the Asian PP market.
For decades, China was the world’s largest destination for imported resin. Increasingly, it is becoming the supplier that shapes regional trade flows instead.
With another 10 million tons/year of new capacity scheduled for 2026-2027, the country’s export surplus appears set to remain a defining feature of the Asian PP market for years to come.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?
- EU publishes tariff regulation, swings doors wide open to duty-free US plastics
- Stats: China rewrites PE trade dynamics as April exports explode amid Middle East disruptions
- Role reversal: Iran seeks polymers from Türkiye amid war disruptions