







China’s import PPH at around 6-month lows, widening discount to locals
by Thi Huong Nguyen - thihuongnguyen@chemorbis.com
In China, the import homo-PP raffia and inj. market has resumed its downtrend following a short break last week. Despite high costs and the approaching high season of Golden September – Silver October, the current weak supply and demand conditions continue to cast a cloud over the market, further compounded by economic challenges faced by players. However, there are some signals of a potential short-term recovery.
ME origins at $860/ton mark emerge after 8 months
Currently, the overall range for import homo-PP raffia and inj. prices is stable on the high end and $30/ton lower on the low end when compared to the previous week, to be reported at $860-950/ton CIF China, cash.
After falling under the $900/ton mark in late July, offers for Middle Eastern origins have continued to decline, further pulling down the import range. This week, several Middle Eastern offers have been seen in the competitive range of $860-880/ton CIF, marking the first time the $860/ton level has re-emerged since the second half of January.
A trader reported these offers noted, “Market participants’ worries about the economic outlook are heightened by the weakening data about the US economy. The return of previously shutdown plants has resulted in higher supply, while demand stays weak. The overall trading environment remains depressed.”
Delta with locals nearly hits year-to-date high
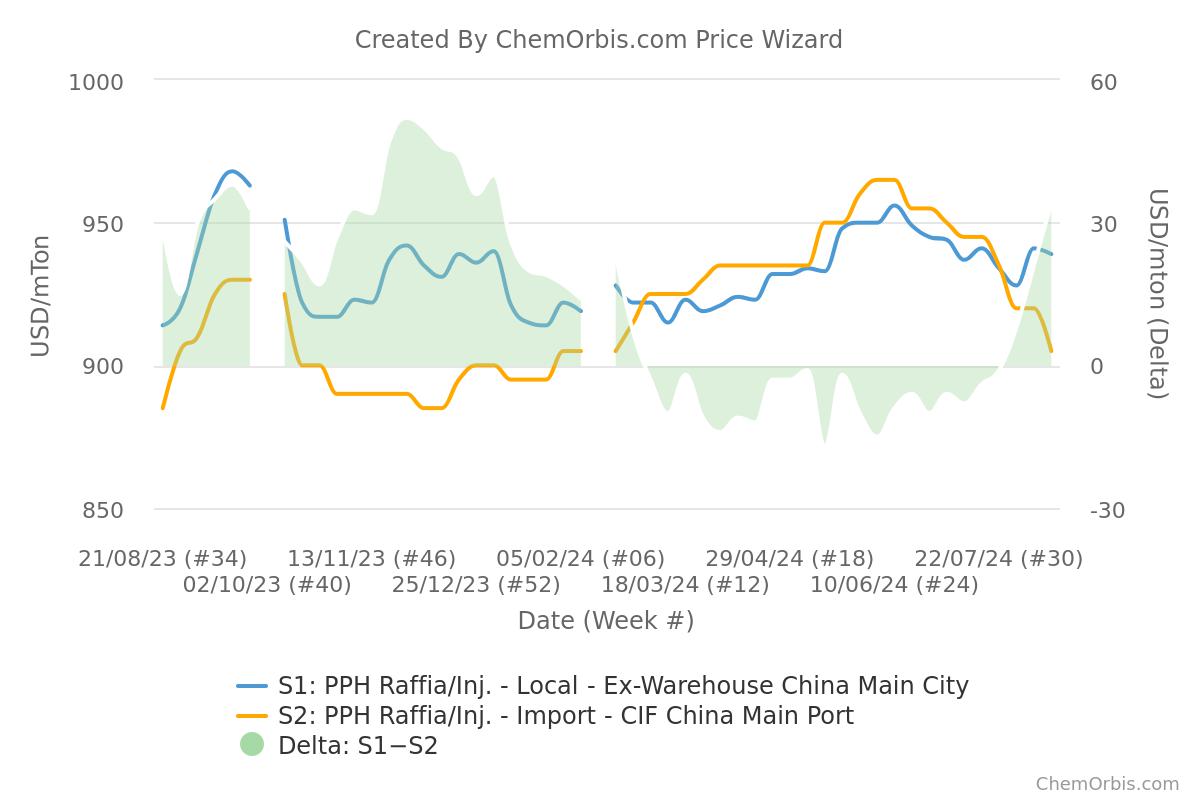
ChemOrbis Price Index data suggests that the weekly average level of homo-PP raffia and inj. prices has dropped to its lowest level since late January. Meanwhile, local prices have mainly retained their stability so far. Therefore, the premium that the latter is carrying over the former roughly widens to a year-to-date high of $34/ton.
As a side note, local prices traded below imports for four months from early March to late July, as shown in the graph below.
PPH-C3 gap at lowest since May 2023
In relation to the upstream market, the delta between CIF China homo-PP raffia and inj. prices and CFR China propylene feedstock costs has kept shrinking to reach its 15-month low of $15/ton, according to ChemOrbis data.
With tightening supply due to cracker turnarounds and run rate cuts, spot propylene prices are expected to remain on a firm footing throughout August and into September, thereby reinforcing production costs for PP. To avoid further margin losses, regional PP producers might refrain from issuing further cuts. “With strong cost support in place, we expect the market to improve in the short term,” said a Zhejiang-based trader.
ME origins at $860/ton mark emerge after 8 months
Currently, the overall range for import homo-PP raffia and inj. prices is stable on the high end and $30/ton lower on the low end when compared to the previous week, to be reported at $860-950/ton CIF China, cash.
After falling under the $900/ton mark in late July, offers for Middle Eastern origins have continued to decline, further pulling down the import range. This week, several Middle Eastern offers have been seen in the competitive range of $860-880/ton CIF, marking the first time the $860/ton level has re-emerged since the second half of January.
A trader reported these offers noted, “Market participants’ worries about the economic outlook are heightened by the weakening data about the US economy. The return of previously shutdown plants has resulted in higher supply, while demand stays weak. The overall trading environment remains depressed.”
Delta with locals nearly hits year-to-date high
ChemOrbis Price Index data suggests that the weekly average level of homo-PP raffia and inj. prices has dropped to its lowest level since late January. Meanwhile, local prices have mainly retained their stability so far. Therefore, the premium that the latter is carrying over the former roughly widens to a year-to-date high of $34/ton.
As a side note, local prices traded below imports for four months from early March to late July, as shown in the graph below.
The growing discount of import prices against locals and the ongoing appreciation of the yuan over the US dollar are likely to encourage import demand to a certain extent, especially with the potential support from the impending peak season.
PPH-C3 gap at lowest since May 2023
In relation to the upstream market, the delta between CIF China homo-PP raffia and inj. prices and CFR China propylene feedstock costs has kept shrinking to reach its 15-month low of $15/ton, according to ChemOrbis data.
With tightening supply due to cracker turnarounds and run rate cuts, spot propylene prices are expected to remain on a firm footing throughout August and into September, thereby reinforcing production costs for PP. To avoid further margin losses, regional PP producers might refrain from issuing further cuts. “With strong cost support in place, we expect the market to improve in the short term,” said a Zhejiang-based trader.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- Europe’s petchem plants close, assets change hands: How far has restructuring progressed?
- Suez recovery gains ground, but global shipping remains far from normal
- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?
