







Domestic PE prices cautiously nudge higher in China
by Thi Huong Nguyen - thihuongnguyen@chemorbis.com
Local PE prices in China followed a stable-to-higher trend during the week ending on December 13, driven by an incremental increase in downstream demand and favorable upstream costs. However, the market atmosphere remained subdued, as buyers limited purchases to essential needs, reflecting cautiousness about the market outlook.
Sellers test markets with HD, LL hikes; LD holds steady
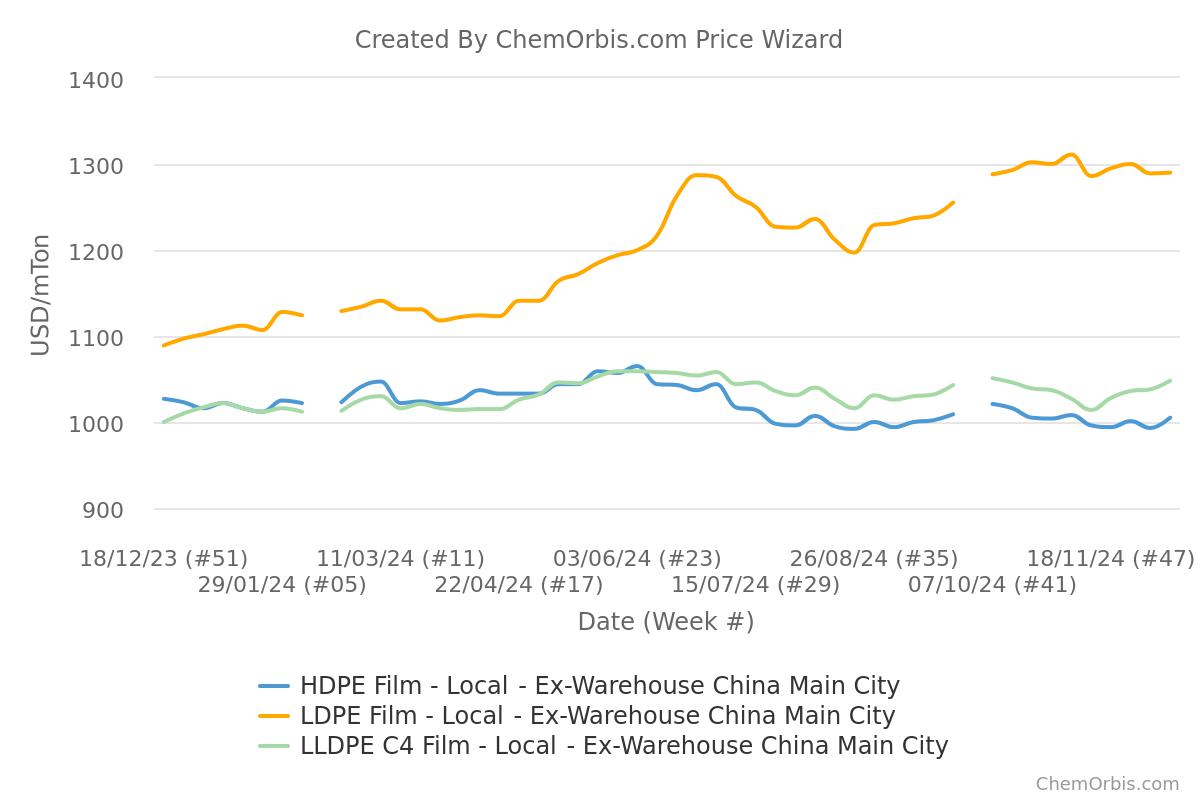
Sellers applied increases of CNY150-200/ton ($21-28/ton) for LLDPE and HDPE film, bringing prices to CNY8400-8800/ton ($1023-1072/ton without VAT) and CNY8000-8500/ton ($974-1035/ton without VAT), respectively, all on an ex-warehouse China, cash including VAT basis. This marked the third consecutive week of increases for LLDPE, while HDPE rebounded from the previous week’s losses.
For LDPE film, domestic prices stabilized, moving sideways after previous declines. Prices were assessed at CNY9970-11200/ton ($1214-1364/ton without VAT) on an ex-warehouse, cash including VAT basis. According to the ChemOrbis Price Index, LDPE maintained significant premiums over LLDPE and HDPE at $242/ton and $285/ton, respectively, underlining HDPE’s weakest position within the PE film market.
Holiday-driven demand, firm costs support sellers
The recent price hikes were primarily driven by cost support and incremental demand improvement. A trader commented, “Local prices for HDPE and LLDPE saw some increases. Cost support remains in place thanks to high naphtha and ethylene prices. Due to the off-season, downstream demand has been in the doldrums, but buying appetite for the upcoming spring festivals has shown incremental improvements.”
The Lunar New Year preparation continued to drive some buying interest from buyers, with a source at a producer saying, “Demand is improving thanks to the upcoming Lunar New Year, as part of buyers are actively making inquiries and sourcing materials with the aim of holiday preparation.”
Besides, feedstock costs for PE production were still firm despite oil’s volatility. According to ChemOrbis Price Wizard data, spot ethylene price was reported at $890/ton CFR China as of December 11, hovering around its eight-and-a-half-month high for the second week.
Sporadic price hikes face pressure from rising supply
Despite the upward adjustments, price hikes were uneven and sporadic, reflecting the lingering weakness in supply-demand dynamics. The off-season and low downstream offtakes limited the impact of holiday-driven demand.
Additionally, availability continued to grow on the back of plant restarts after maintenance shutdowns, and supply concerns remained in place due to awaiting capacity additions.
Another trader noted, “Supply-demand dynamics are not favorable for high prices. Supply is lengthening at home, as more plants restart from their turnarounds. More buyers restock their inventories ahead of the holiday; however, the follow-up demand has yet to experience strong recovery, and actual purchases remain limited to essential needs.”
According to market players, the two major producers’ combined polyolefin inventories were at 620,000 tons on December 13, marginally rising by 10,000 tons from last week. In the meantime, China is set to add 2.05 million tons/year of new PE capacity by the end of December, according to ChemOrbis Production News Pro. These factors highlight the challenges sellers face in sustaining higher prices amid expanding domestic supply.
Sellers test markets with HD, LL hikes; LD holds steady
Sellers applied increases of CNY150-200/ton ($21-28/ton) for LLDPE and HDPE film, bringing prices to CNY8400-8800/ton ($1023-1072/ton without VAT) and CNY8000-8500/ton ($974-1035/ton without VAT), respectively, all on an ex-warehouse China, cash including VAT basis. This marked the third consecutive week of increases for LLDPE, while HDPE rebounded from the previous week’s losses.
For LDPE film, domestic prices stabilized, moving sideways after previous declines. Prices were assessed at CNY9970-11200/ton ($1214-1364/ton without VAT) on an ex-warehouse, cash including VAT basis. According to the ChemOrbis Price Index, LDPE maintained significant premiums over LLDPE and HDPE at $242/ton and $285/ton, respectively, underlining HDPE’s weakest position within the PE film market.
Holiday-driven demand, firm costs support sellers
The recent price hikes were primarily driven by cost support and incremental demand improvement. A trader commented, “Local prices for HDPE and LLDPE saw some increases. Cost support remains in place thanks to high naphtha and ethylene prices. Due to the off-season, downstream demand has been in the doldrums, but buying appetite for the upcoming spring festivals has shown incremental improvements.”
The Lunar New Year preparation continued to drive some buying interest from buyers, with a source at a producer saying, “Demand is improving thanks to the upcoming Lunar New Year, as part of buyers are actively making inquiries and sourcing materials with the aim of holiday preparation.”
Besides, feedstock costs for PE production were still firm despite oil’s volatility. According to ChemOrbis Price Wizard data, spot ethylene price was reported at $890/ton CFR China as of December 11, hovering around its eight-and-a-half-month high for the second week.
Sporadic price hikes face pressure from rising supply
Despite the upward adjustments, price hikes were uneven and sporadic, reflecting the lingering weakness in supply-demand dynamics. The off-season and low downstream offtakes limited the impact of holiday-driven demand.
Additionally, availability continued to grow on the back of plant restarts after maintenance shutdowns, and supply concerns remained in place due to awaiting capacity additions.
Another trader noted, “Supply-demand dynamics are not favorable for high prices. Supply is lengthening at home, as more plants restart from their turnarounds. More buyers restock their inventories ahead of the holiday; however, the follow-up demand has yet to experience strong recovery, and actual purchases remain limited to essential needs.”
According to market players, the two major producers’ combined polyolefin inventories were at 620,000 tons on December 13, marginally rising by 10,000 tons from last week. In the meantime, China is set to add 2.05 million tons/year of new PE capacity by the end of December, according to ChemOrbis Production News Pro. These factors highlight the challenges sellers face in sustaining higher prices amid expanding domestic supply.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- Europe’s petchem plants close, assets change hands: How far has restructuring progressed?
- Suez recovery gains ground, but global shipping remains far from normal
- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?

