






PP, PE restarts emerge across Mid-East, but supply remains fragile
by Esra Ersöz - eersoz@chemorbis.com
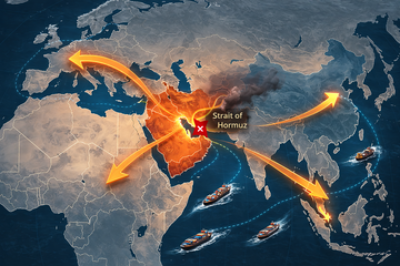
The rally driven by the Middle East supply-shock— which pushed PP and PE prices to record or pandemic-era highs across Asia and Europe — started to crack three weeks ago as China began taking advantage of widening arbitrage opportunities. Since then, Middle Eastern PP and PE offers have also started to ease. The return of some PP and PE plants in the Middle East, together with inventory sales and delayed cargo arrivals, has also helped calm earlier shortage fears.
Still, supply continues to rely heavily on inventories, postponed shipments, and selective spot sales rather than stable production flows.
Land bridge logistics and feedstock disruptions continue to expose structural vulnerabilities
Market participants said land bridge options via Jeddah Port are still widely used for cargoes from Dammam and Jubail, Bahrain, and Kuwait as shipping conditions through the Strait of Hormuz remain problematic.
Meanwhile, according to market sources, Saudi Aramco has yet to fully normalize ethane and propane supply to downstream plants following the April 7 strikes on Jubail Industrial City, one of the world’s largest petrochemical hubs on the east coast of the Arab peninsula.
Who is off, who is back on in Jubail?
Saudi Polymers has resumed PP and PE production, while APC restarted one PP line and SHARQ entered restart mode ahead of a possible mid-May return. However, several major assets including Ibn Zahr, Kayan, Sadara, SEPC and Saudi Polyolefins remain shut or under force majeure, highlighting that the recovery process remains uneven.
QatarEnergy’s PE site remains largely offline despite one LDPE unit operating, while Equate in Kuwait continues to face production disruptions under force majeure. In the UAE, Borouge has restarted operations following the Ruwais strike, although PE production rates are reportedly lower than normal.
West coast producers continue operating normally
Market players noted that PP and PE facilities on the western coast of the Arabian Peninsula — including PetroRabigh, YANPET, YANSAB and NATPET — have continued normal production and shipment activities despite the April 10 strike on the SAMREF refinery in Yanbu.
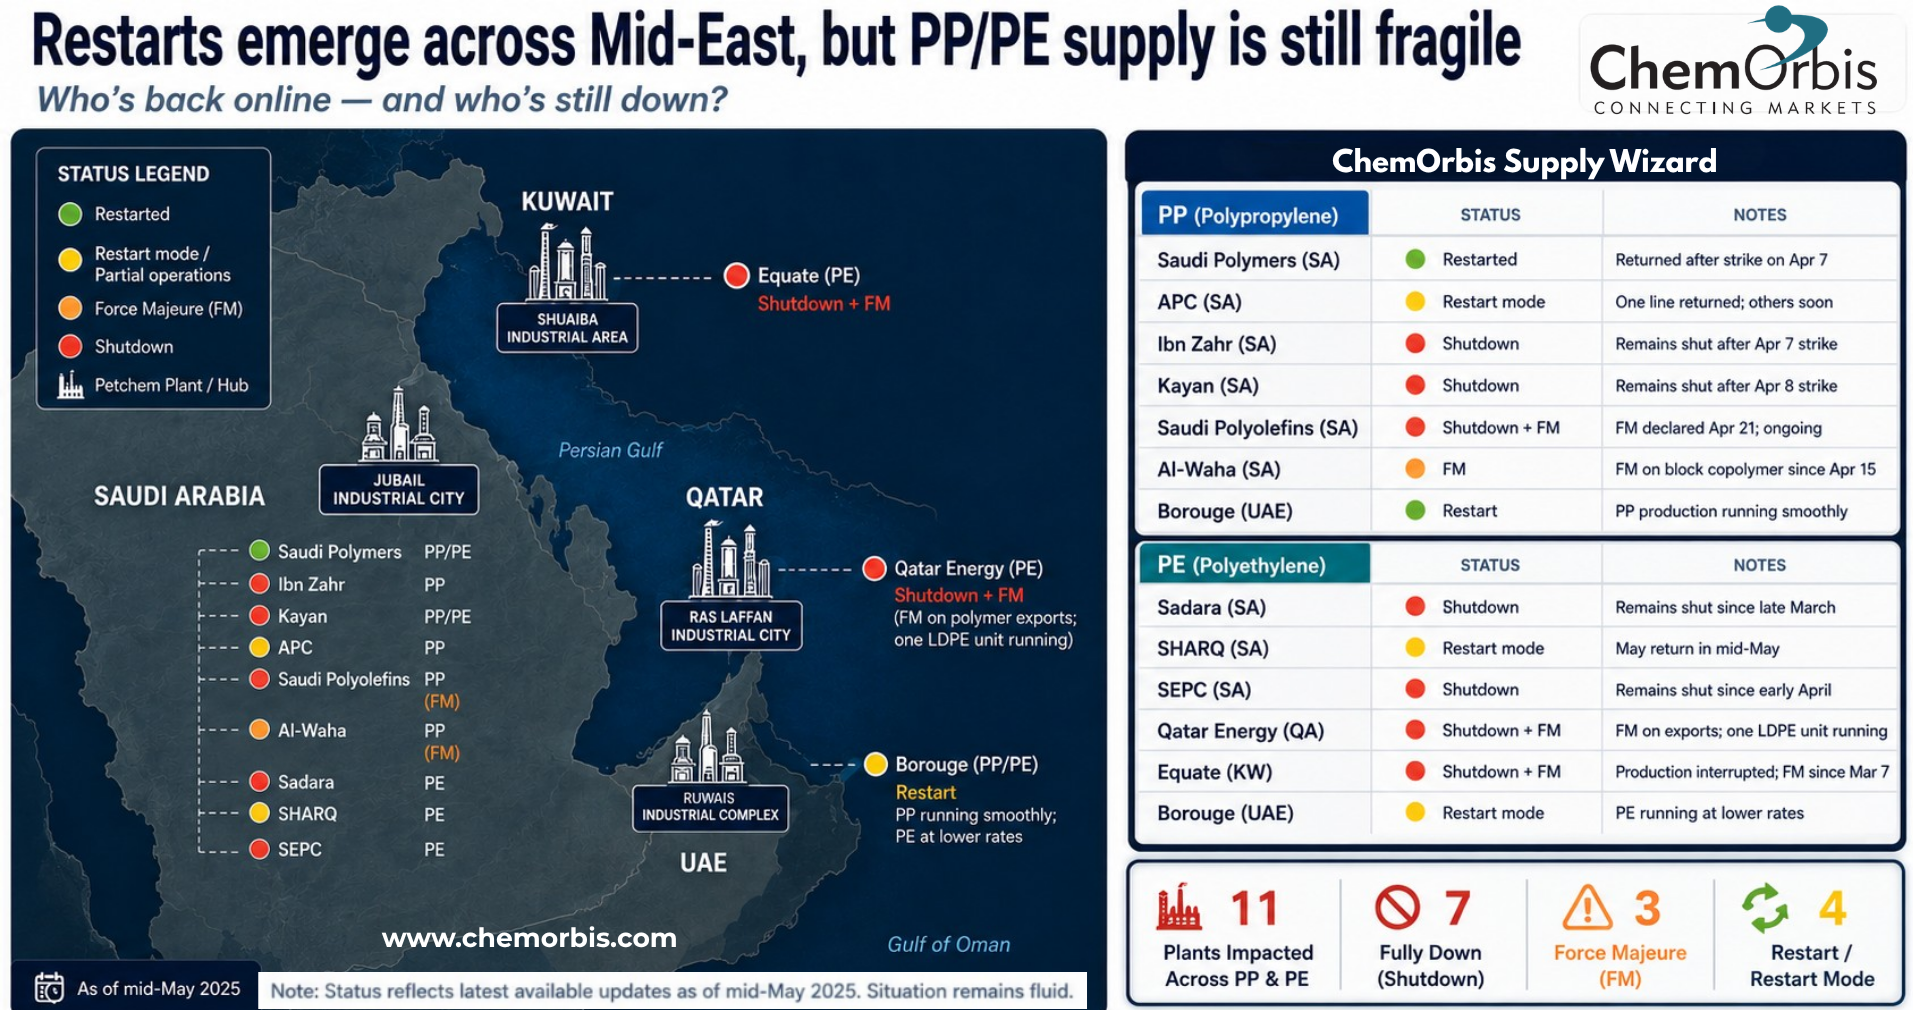
* More details about production capacities, locations and dates as well data about offline and new capacities are available on ChemOrbis Supply Wizard.
PP non-woven, copolymer, PPH film supply remains the tightest segment
Structural supply risks have not fully disappeared, with non-woven PP and certain PP copolymers continuing to face tighter availability than fibre and raffia grades in Türkiye. Still, slower downstream activity and approaching holidays have reduced the sense of urgency among buyers. One converter said, “People have material on the way, while demand itself is missing.”
In Egypt, meanwhile, PPH film prices remained elevated despite the ease in other PP grades, supported by extremely tight availability.
Turkish traders said PE price declines may begin losing momentum if demand improves after the holiday period. Ongoing uncertainty surrounding the Strait of Hormuz, alongside still-offline capacities and accumulated production losses, may provide underlying support to the market.
Still, supply continues to rely heavily on inventories, postponed shipments, and selective spot sales rather than stable production flows.
Land bridge logistics and feedstock disruptions continue to expose structural vulnerabilities
Market participants said land bridge options via Jeddah Port are still widely used for cargoes from Dammam and Jubail, Bahrain, and Kuwait as shipping conditions through the Strait of Hormuz remain problematic.
Meanwhile, according to market sources, Saudi Aramco has yet to fully normalize ethane and propane supply to downstream plants following the April 7 strikes on Jubail Industrial City, one of the world’s largest petrochemical hubs on the east coast of the Arab peninsula.
Who is off, who is back on in Jubail?
Saudi Polymers has resumed PP and PE production, while APC restarted one PP line and SHARQ entered restart mode ahead of a possible mid-May return. However, several major assets including Ibn Zahr, Kayan, Sadara, SEPC and Saudi Polyolefins remain shut or under force majeure, highlighting that the recovery process remains uneven.
QatarEnergy’s PE site remains largely offline despite one LDPE unit operating, while Equate in Kuwait continues to face production disruptions under force majeure. In the UAE, Borouge has restarted operations following the Ruwais strike, although PE production rates are reportedly lower than normal.
West coast producers continue operating normally
Market players noted that PP and PE facilities on the western coast of the Arabian Peninsula — including PetroRabigh, YANPET, YANSAB and NATPET — have continued normal production and shipment activities despite the April 10 strike on the SAMREF refinery in Yanbu.
* More details about production capacities, locations and dates as well data about offline and new capacities are available on ChemOrbis Supply Wizard.
PP non-woven, copolymer, PPH film supply remains the tightest segment
Structural supply risks have not fully disappeared, with non-woven PP and certain PP copolymers continuing to face tighter availability than fibre and raffia grades in Türkiye. Still, slower downstream activity and approaching holidays have reduced the sense of urgency among buyers. One converter said, “People have material on the way, while demand itself is missing.”
In Egypt, meanwhile, PPH film prices remained elevated despite the ease in other PP grades, supported by extremely tight availability.
Turkish traders said PE price declines may begin losing momentum if demand improves after the holiday period. Ongoing uncertainty surrounding the Strait of Hormuz, alongside still-offline capacities and accumulated production losses, may provide underlying support to the market.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- Suez recovery gains ground, but global shipping remains far from normal
- Saudi pipeline outage compounds supply and logistics risks, fueling PP, PE rally
- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?
- EU publishes tariff regulation, swings doors wide open to duty-free US plastics
