







Post-holiday import PP, PE markets rise on reducing supply in SE Asia
by Thi Huong Nguyen - thihuongnguyen@chemorbis.com
Major Asian polymer markets reopened after the Lunar New Year holiday last week. While import PP and PE markets largely stayed rangebound in China, Southeast Asia witnessed renewed increases, driven by tightening supplies. Nonetheless, persistently weak downstream demand raised questions about the sustainability of the recent uptrend.
Sellers seek hikes of up to around $40/ton
Following the extended holiday, PPBC injection prices largely maintained their pre-holiday levels, while the overall range for homo-PP raffia and injection was stable on the low end and $30/ton higher on the high end. The latest hikes came along with higher offers in Vietnam, where import homo-PP raffia and inj. prices above the $1000/ton mark resurfaced for the first time in around six months.
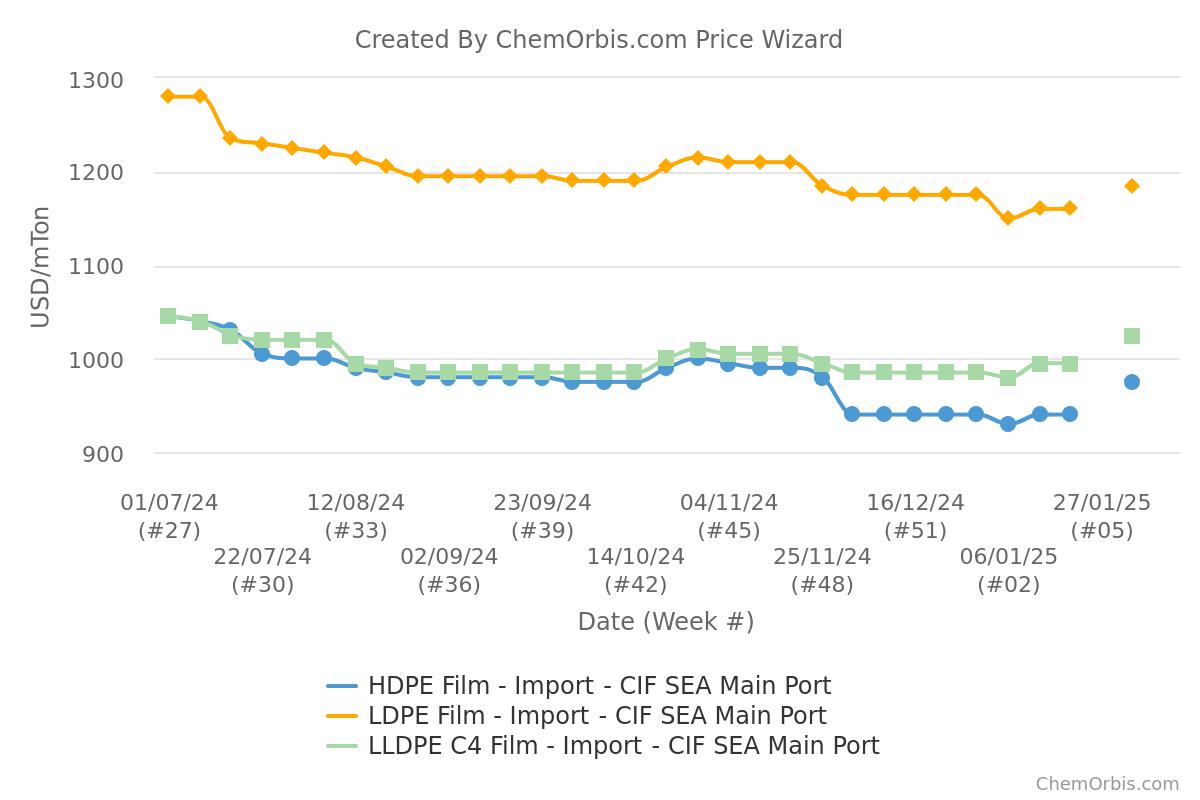
In the meantime, PE experienced more pronounced increases than PP, with prices climbing on both ends. Compared to the pre-holiday week, import price ranges for all origins were $10-40/ton higher for LDPE film, $30/ton higher for LLDPE film, and $30-40/ton higher for HDPE film. According to weekly average prices obtained from ChemOrbis Price Index, LDPE and HDPE reached their highest levels since late November, while LLDPE hit a nearly seven-month high.
Supply shortages expected to persist
Maintenance shutdowns and production cuts across the region have tightened supply, giving sellers the upper hand. Market participants anticipate further supply constraints due to plant turnarounds across Asia and the Middle East, reinforcing firm pricing sentiment.
Taiwan’s Formosa Plastics Corp. reduced operating rates at four PP units from January to March, while South Korea’s Lotte Chemical planned to run its PP, HDPE, and LDPE plants at lower rates until mid-March, according to ChemOrbis Production News Pro. China also faced significant PP and PE capacity losses in February despite the inventory buildup during the week-long holiday.
In Southeast Asia, Hyosung Corporation shut its Ba Ria-Vung Tau complex, including a 300,000 tons/year PP unit, for planned maintenance from February 1 to March 1. Malaysia’s PRefChem experienced an unplanned shutdown at its No. 2 PP facility in Pengerang, with no confirmed restart date. Additionally, low margins forced Lotte Chemical Titan to shut some PP and PE plants in Pasir Gudang, Malaysia, in January, with restart dates expected in mid-March.
In the Middle East, a Saudi producer reported production issues at four polyolefin lines, while market players highlighted potential disruptions due to Borouge’s PE plant shutdown in Abu Dhabi.
Weak demand clouds market outlook
Despite supply constraints, demand in Southeast Asia’s polyolefin markets remained sluggish post-holiday, limiting the sustainability of price hikes. Buyers focused on meeting immediate needs rather than building inventories, reflecting a cautious sentiment.
A Malaysian trader commented, “HDPE film supplies are limited. However, buyers are still cautious, buying only based on immediate requirements.” A Vietnam-based trader added, “Markets are quiet, with limited import offers. Many players have just returned from the holiday and are taking a wait-and-see approach due to sufficient stock on hand.”
Additionally, the US’s 10% tariff on Chinese goods raised concerns about its broader economic impact, which could weigh on Southeast Asia’s markets and further limit polyolefin demand.
Sellers seek hikes of up to around $40/ton
Following the extended holiday, PPBC injection prices largely maintained their pre-holiday levels, while the overall range for homo-PP raffia and injection was stable on the low end and $30/ton higher on the high end. The latest hikes came along with higher offers in Vietnam, where import homo-PP raffia and inj. prices above the $1000/ton mark resurfaced for the first time in around six months.
In the meantime, PE experienced more pronounced increases than PP, with prices climbing on both ends. Compared to the pre-holiday week, import price ranges for all origins were $10-40/ton higher for LDPE film, $30/ton higher for LLDPE film, and $30-40/ton higher for HDPE film. According to weekly average prices obtained from ChemOrbis Price Index, LDPE and HDPE reached their highest levels since late November, while LLDPE hit a nearly seven-month high.
Supply shortages expected to persist
Maintenance shutdowns and production cuts across the region have tightened supply, giving sellers the upper hand. Market participants anticipate further supply constraints due to plant turnarounds across Asia and the Middle East, reinforcing firm pricing sentiment.
Taiwan’s Formosa Plastics Corp. reduced operating rates at four PP units from January to March, while South Korea’s Lotte Chemical planned to run its PP, HDPE, and LDPE plants at lower rates until mid-March, according to ChemOrbis Production News Pro. China also faced significant PP and PE capacity losses in February despite the inventory buildup during the week-long holiday.
In Southeast Asia, Hyosung Corporation shut its Ba Ria-Vung Tau complex, including a 300,000 tons/year PP unit, for planned maintenance from February 1 to March 1. Malaysia’s PRefChem experienced an unplanned shutdown at its No. 2 PP facility in Pengerang, with no confirmed restart date. Additionally, low margins forced Lotte Chemical Titan to shut some PP and PE plants in Pasir Gudang, Malaysia, in January, with restart dates expected in mid-March.
In the Middle East, a Saudi producer reported production issues at four polyolefin lines, while market players highlighted potential disruptions due to Borouge’s PE plant shutdown in Abu Dhabi.
Weak demand clouds market outlook
Despite supply constraints, demand in Southeast Asia’s polyolefin markets remained sluggish post-holiday, limiting the sustainability of price hikes. Buyers focused on meeting immediate needs rather than building inventories, reflecting a cautious sentiment.
A Malaysian trader commented, “HDPE film supplies are limited. However, buyers are still cautious, buying only based on immediate requirements.” A Vietnam-based trader added, “Markets are quiet, with limited import offers. Many players have just returned from the holiday and are taking a wait-and-see approach due to sufficient stock on hand.”
Additionally, the US’s 10% tariff on Chinese goods raised concerns about its broader economic impact, which could weigh on Southeast Asia’s markets and further limit polyolefin demand.
More free plastics news
Plastic resin (PP, LDPE, LLDPE ,HDPE, PVC, GPS; HIPS, PET, ABS) prices, polymer market trends, and more...- S Korea’s petchem restructuring moves from talks to closures
- European natural gas, Asian LNG hit fresh highs amid Middle East tensions
- Global shipping faces persistent bottlenecks across major trade routes
- War or recovery? H1 earnings reshuffle petchem winners and losers
- Oil roller coaster in July H2 fails to derail most polymer rallies
- Dow’s €1.1 billion claim puts Europe’s ethylene cartel dispute back in focus
- Crude oil surges on renewed war premium; will it reverse the polymer slump?
- EU publishes tariff regulation, swings doors wide open to duty-free US plastics
- Stats: China rewrites PE trade dynamics as April exports explode amid Middle East disruptions
- Role reversal: Iran seeks polymers from Türkiye amid war disruptions

